




Porsche is preparing for a future in which selling fewer cars could be more profitable than chasing the volumes it once enjoyed. The German sports-car maker wants to lift the average selling price of its most exclusive models by roughly 20 per cent, pushing them further into territory traditionally occupied by ultra-luxury brands.
At the same time, Porsche is shrinking. About 9,000 positions are scheduled to disappear by 2035 as the company cuts costs, simplifies its product range and adjusts to weaker demand, particularly in China. The two moves are connected. Porsche’s new strategy assumes that the company may never return quickly to its previous sales highs, so management is betting that richer specifications, bespoke cars and higher-margin sports models can generate more profit from every vehicle that leaves the factory.
The 20% Price Goal Is Not a Blanket Increase
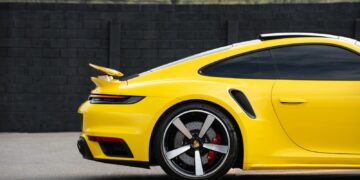
Porsche’s plan is more nuanced than simply adding 20 per cent to every window sticker. The company says it wants to increase the average selling price of its top-of-the-range models by about 20 per cent over the medium term. Reporting from its October 7 capital-markets presentation puts the current average for those cars at roughly €270,000, with Porsche aiming for more than €330,000 by the end of the decade.
That increase can come from several places. More expensive derivatives can occupy a larger portion of the sales mix, customers can purchase additional factory options, and Porsche can sell more limited-production or individually commissioned cars. The company also wants higher-end models to represent a substantially larger part of its portfolio. For a wealthy customer ordering a 911, that could mean being steered toward a GT, Turbo or highly personalized version rather than a comparatively conventional specification. In other words, Porsche is trying to increase what each affluent customer spends—not merely raise every base price by the same percentage.
Porsche Is Preparing to Sell Fewer Cars
The strategy represents a striking change from Porsche’s recent growth years. Global deliveries reached a record 320,221 vehicles in 2023 before declining to 310,718 in 2024 and 279,449 in 2025. Porsche now says it wants a cost structure capable of breaking even at fewer than 200,000 vehicles annually. That would give the company far more breathing room if demand remains permanently below its earlier peak.
The shift is summarized internally as “Value over Volume.” Instead of building the business around continually increasing unit sales, Porsche wants revenue and earnings to depend more heavily on the value of each vehicle. The approach already has an encouraging example in the 911. While total Porsche deliveries dropped 16 per cent during the first half of 2026, 911 deliveries rose 19 per cent to 30,534. That does not prove expensive sports cars can compensate for every lost SUV sale, but it illustrates why management sees an opportunity in customers who remain willing to spend heavily on distinctive, high-performance products even when the broader market weakens.
The 9,000 Positions Will Be Cut Over Years, Not Overnight
The workforce reduction is large, but the timing needs clarification. Porsche is not dismissing 9,000 employees at once. Its restructuring plans call for roughly 9,000 positions to be eliminated by 2035, equivalent to around one-fifth of the approximately 42,600 people Porsche employed at the end of 2024. The newest agreement accounts for a further 5,000 jobs, on top of an earlier 3,900-position reduction programme and about 500 positions connected with subsidiary closures.
Porsche says the additional 5,000 reductions are intended to occur largely through natural attrition, demographic changes, expanded partial-retirement arrangements and voluntary severance rather than compulsory layoffs. Its agreement with employee representatives also extends protection against compulsory redundancies for the core workforce through 2035. At the same time, employees are making other concessions, including changes to bonuses and future wage increases. For someone working at Zuffenhausen or Weissach, the restructuring therefore may not look like a traditional factory closure. It is a long, managed contraction designed to leave Porsche with a considerably smaller permanent cost base.
A Collapse From 14.1% to 1.1% Explains the Urgency
The financial numbers show why management is prepared to make such extensive changes. Porsche generated €36.27 billion in revenue during 2025, down from €40.08 billion in 2024. Operating profit suffered a far steeper collapse, falling from €5.64 billion to just €413 million. Its operating return on sales dropped from 14.1 per cent to only 1.1 per cent. In 2023, that same margin had been 18 per cent.
Not all of the deterioration reflected the underlying profitability of selling cars. Porsche reported approximately €3.9 billion in extraordinary 2025 expenses. About €2.4 billion was related to restructuring its product strategy and rescaling the company, roughly €700 million came from battery-related activities and another €700 million reflected U.S. tariffs. There are already signs of improvement: during the first half of 2026, operating profit increased to €1.35 billion and the operating margin recovered to 7.8 per cent. Still, those results remain far below the profitability Porsche enjoyed only a few years ago, explaining why management is unwilling to rely on a simple sales rebound.
China Has Gone From Growth Engine to Major Problem
Few markets illustrate Porsche’s changing circumstances better than China. In 2021, the country was Porsche’s largest individual market for a seventh consecutive year, with 95,671 deliveries. That number fell to 79,283 in 2023, 56,887 in 2024 and only 41,938 in 2025. During the first half of 2026, Porsche delivered another 14,501 vehicles there, 32 per cent fewer than during the same period a year earlier.
The problem extends beyond a temporary economic slowdown. Chinese consumers have access to increasingly sophisticated domestic premium and electric vehicles, intensifying competition for European luxury brands. Porsche has responded by refusing to chase volume through heavy discounting, preferring what it calls value-oriented sales. Its new break-even target below 200,000 vehicles is explicitly based on a very conservative outlook for China. That is a remarkable reversal for a company that once sold almost 100,000 vehicles annually in the country. Porsche’s new strategy effectively assumes that one of its former growth engines may remain much smaller, forcing the rest of the business to become more profitable.
Ferrari Offers a Tempting Blueprint
Porsche’s move upmarket inevitably invites comparisons with Ferrari—and there is a personal connection. Porsche CEO Michael Leiters took over in January 2026 after serving as McLaren Automotive’s chief executive. Before McLaren, he spent more than eight years as Ferrari’s chief technology officer. He therefore arrives with direct experience inside businesses where exclusivity can be considerably more important than sheer production volume.
Ferrari demonstrates why that model is attractive. It shipped only 13,640 cars in 2025, a tiny fraction of Porsche’s 279,449 deliveries, yet generated €7.15 billion in revenue and an operating profit of €2.11 billion. Its EBIT margin reached 29.5 per cent. Ferrari specifically credited product mix and personalisation for helping its financial performance. Porsche cannot simply recreate those economics: it has a much larger factory system, dealer network and product range stretching from sports cars to high-volume SUVs. But the lesson is obvious. If wealthy customers will pay dramatically more for exclusivity, special specifications and scarcity, selling fewer cars does not necessarily mean earning less money.
Customization Is Becoming a Much Bigger Business
One of Porsche’s clearest opportunities involves buyers who want a car unlike anyone else’s. The company intends to increase revenue from its highly individualized Sonderwunsch business sixfold over the medium term. It is also expanding Porsche Exclusive Manufaktur and bringing customization, heritage and performance activities under a broader “Home of Sports Cars” strategy. Porsche’s ownership stake in racing specialist Manthey is being increased to 67 per cent as performance kits and more specialized vehicle concepts become more important.
This approach changes the economics of an already expensive car. A buyer may begin with a 911 but then choose custom paint, unusual interior materials, heritage-inspired details, performance equipment or a much more extensive factory commission. Some of those purchases can add significant value without requiring Porsche to develop an entirely separate mass-market model. At the same time, the company plans to reduce its overall number of model variants by about 20 per cent while increasing average sales per remaining variant by roughly 30 per cent. The goal is a simpler factory portfolio paired with far more possibilities for customers willing to pay for individuality.
Fewer Mainstream Variants Will Sit Beside More Halo Cars
Simplification does not mean Porsche intends to stop creating exotic products. Quite the opposite. The company wants high-margin D- and E-segment vehicles to make up a much larger share of its portfolio. It has announced plans for a mid-engined super-sports-car architecture capable of supporting a model positioned above the 911, while also considering an SUV above the Cayenne. Porsche says it intends to introduce at least one “brand-defining” new product every year through 2030.
The 911 itself will receive more exclusive derivatives, giving Porsche additional opportunities to sell expensive versions of its best-known model. This creates an unusual product strategy: fewer permutations overall, but more attention directed toward the vehicles that generate excitement and stronger margins. A customer walking into a dealership several years from now may encounter fewer subtly different versions of ordinary models while seeing more limited, high-performance or highly personalized flagships. Porsche is effectively betting that too much complexity costs money, while genuine exclusivity creates pricing power. Those are very different kinds of variety, even though both can produce long option lists.
The Electric-Vehicle Strategy Has Become More Flexible
Porsche’s restructuring also marks a retreat from the idea that its future could rapidly become overwhelmingly electric. The company now emphasizes three parallel powertrain paths: combustion engines, plug-in hybrids and battery-electric vehicles. Electric versions of the 718 Boxster and Cayman remain planned, while a new smaller SUV scheduled for 2028 is expected to offer combustion and plug-in-hybrid power alongside the electric Macan already on sale.
The numbers help explain that flexibility. Battery-electric vehicles represented 19.4 per cent of Porsche’s automotive sales mix during the first half of 2026, down from 23.5 per cent a year earlier. Porsche has also acknowledged that the adoption of electromobility has developed more slowly than previously expected in some markets. The company spent heavily revising its earlier product plans, with battery activities and strategic realignment contributing billions of euros to 2025’s exceptional expenses. None of this means Porsche is abandoning EVs. Instead, management is trying to avoid depending on a single propulsion technology while customer preferences, regulations and charging infrastructure continue to evolve at different speeds around the world.
Cost Cutting Extends Far Beyond the 9,000 Jobs
The workforce reductions attract the most attention, but Porsche’s restructuring reaches almost every part of the organization. Management positions are targeted to fall by 40 per cent over the medium term. Development costs for future model lines are supposed to decline by as much as 20 per cent, while sales and distribution costs are also targeted for a 20 per cent reduction. Porsche wants production personnel costs down by as much as 30 per cent and material costs on new vehicle projects about 10 per cent below previous plans.
Greater cooperation with Audi is another part of the equation. Porsche intends to make greater use of shared PPE and PPC architectures, allowing engineering resources and components to be used more efficiently while preserving brand-specific features. Its sales organization is also being simplified from five regions to four. For engineers, managers and factory staff, this means the turnaround is about far more than changing vehicle prices. Porsche is attempting to redesign the company around fewer layers, fewer variants, more shared technology and lower fixed costs. The expensive cars are only one side of a much broader restructuring.
The Gamble Is Whether Exclusivity Can Restore Porsche-Level Profits
Porsche’s medium-term ambition is to restore an operating return on sales of between 10 and 15 per cent, eventually reaching a long-term target of 15 per cent. It also wants medium-term group revenue of €41 billion to €45 billion and an automotive net-cash-flow margin between 9 and 12 per cent. Achieving those targets while preparing to break even below 200,000 annual vehicles shows just how much management expects higher value per car to matter.
There is no guarantee the strategy will work. Porsche must persuade customers that higher prices come with genuine additional desirability rather than simple markups. It must rebuild profitability while cutting jobs without weakening engineering, quality or customer service. China could remain difficult, tariffs could persist and expensive new products still carry development risk. Yet the underlying calculation is clear. Porsche no longer wants its future to depend on returning to 320,000 annual deliveries. It wants a smaller, leaner company capable of making much more money from each desirable car—and wealthy customers willing to pay more for the privilege of owning one.