




A date that once looked like a negotiating threat is now sitting uncomfortably close to the auto industry’s 2027 production calendar. President Donald Trump said on August 24 that U.S. tariffs on Canadian cars, trucks and automotive parts would rise to 50% on January 1, 2027, after Canada-U.S. trade talks broke down. The proposed increase would come amid a tariff environment that has already forced automakers to rethink sourcing, pricing and plant strategy across North America.
The 50% rate is not yet a finalized across-the-board January policy, and industry executives still see room for a deal. But automakers cannot plan factories one week at a time. Vehicle allocation, supplier contracts and parts flows are set months in advance, making January 1 a practical planning deadline even if negotiations ultimately change what happens at the border.
January 1 Is Now More Than a Political Talking Point
The January 1 date matters because the industry had been expecting movement in the opposite direction. Reuters reported that the trade deal under discussion before talks collapsed would have lowered the top-line U.S. tariff on Canadian cars and light-duty trucks from 25% to 15%. Instead, Trump threatened to raise tariffs on Canadian cars, trucks and automotive parts to 50% beginning January 1. The dispute included disagreement over treatment of medium- and heavy-duty trucks, a category that matters to Canadian plants as well as to U.S. commercial-vehicle buyers.
The current rules are already complicated. Under the U.S. auto tariff system introduced in 2025, qualifying USMCA vehicles can have the 25% duty applied only to their non-U.S. content after approval. Trump’s August announcement did not spell out all of the mechanics that would govern a 50% rate. That missing detail is important: automakers need to model both the headline rate and whether existing treatment for U.S. content would survive.
Canada’s Auto Industry Is Built Around the U.S. Market
Canada’s auto sector is unusually dependent on the American market. Statistics Canada reported that more than 93% of Canadian motor-vehicle exports went to the United States in 2025, even after exports to the U.S. fell 9.6% from the previous year. Its value-added analysis found that U.S. demand accounted for 76.4% of payroll jobs in Canada’s automobile and light-duty vehicle manufacturing industry in 2024. That represents roughly 27,000 assembly-related jobs tied directly or indirectly to American demand before counting the broader supplier and dealership network.
The scale is large enough that even a relatively small Canadian share of the U.S. vehicle market matters. ISED trade data show that Canadian motor-vehicle manufacturing exports to the United States were worth about C$45.2 billion in 2025. Reuters, citing Barclays, said Canadian-built vehicles represented only about 6% of U.S. vehicle sales that year. The exposure is therefore concentrated rather than universal: a tariff shock would land hardest on specific high-volume models, plants and suppliers.
Detroit Brands Face Model-Level Exposure
For the Detroit automakers, the problem is not simply “Canada” as a single production location. It is the individual products tied to Canadian plants. Barclays estimated that about 17% of Chevrolet Silverado production was in Canada. Stellantis builds the Chrysler Pacifica in Canada, while Ford has added F-Series Super Duty production at Oakville, Ontario. Ford’s original plan called for up to 100,000 Super Duty trucks a year at Oakville, making the plant part of a North American network that also includes major U.S. truck operations.
That network shows why moving production is not a simple switch. Ford said its Oakville expansion involved about C$2.3 billion in plant investment and would secure roughly 1,800 Canadian jobs. At the same time, 10 U.S. plants in five states support Super Duty production and employ about 20,000 American workers. A tariff on the Canadian-built truck therefore does not isolate one Canadian factory; it changes the economics of a product supported by powertrain, transmission, axle and component operations on both sides of the border.
Toyota and Honda May Have the Most Direct Exposure
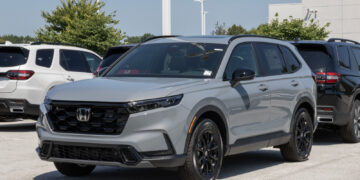
Toyota and Honda could be even more exposed than the Detroit companies. Reuters reported that the two Japanese automakers account for more than three-quarters of vehicles made in Canada. Barclays estimated that Canadian-built vehicles represented almost one-quarter of Honda’s U.S. sales last year and 17% of Toyota’s. Canadian plants ship models such as the Honda CR-V and Toyota RAV4 into the U.S., putting two of the companies’ most important North American nameplates directly in the tariff conversation.
Analysts cited by Reuters said a 50% tariff could force Toyota and Honda to shut some Canadian production lines if it took effect as proposed. The companies have not announced such shutdowns, which is an important distinction. Honda has, however, linked future North American investment to trade certainty: Executive Vice President Noriya Kaihara said the company might change direction on a potential eighth North American assembly plant if USMCA arrangements are not extended. That turns tariff uncertainty from a short-term pricing issue into a long-term factory-location question.
The Parts Problem Could Be Bigger Than the Vehicle Tariff
The most disruptive part of the threat may be the inclusion of automotive parts. Canadian and U.S. auto manufacturing has evolved around components moving back and forth across the border rather than staying inside one country. Canadian government briefing material estimates that Canadian-built vehicles contain about 50% U.S. content by value. Ottawa has also documented that some components can cross the border as many as six times before final assembly. In that system, a tariff on Canadian parts can eventually feed back into the cost of a vehicle assembled in Michigan, Ohio or another U.S. manufacturing state.
The numbers help explain the concern. Canada imported nearly C$30 billion in automotive parts from the United States in 2024, while Statistics Canada found that Canadian auto-parts exports to the U.S. still rose 2.3% in 2025 even as finished-vehicle exports declined. Flavio Volpe of Canada’s Automotive Parts Manufacturers’ Association argued that a tariff on Canadian parts would ultimately be borne by U.S. assembly operations that depend on those inputs. The exact impact would vary by component and tariff treatment, but the supply-chain exposure is substantial.
Tariff Costs Are Already Measured in Billions
Automakers are approaching the January threat after already absorbing large tariff bills. Reuters reported in August that General Motors expected gross tariff-related expenses of roughly US$2.5 billion to US$3.5 billion in 2026, while Ford estimated a net tariff hit of about US$1 billion. Those figures cover the broader tariff environment, not only Canada, but they show why another major increase is difficult for finance teams to treat as a distant hypothetical. Tariff exposure is already appearing in operating plans and profit forecasts.
Detroit executives have another concern: relative treatment. Reuters reported that vehicles imported from Japan, South Korea and Europe were facing 15% tariffs under separate arrangements, while imports from Canada and Mexico remained around 25%, with some relief tied to U.S. content. Automaker estimates cited by Reuters also suggested proposed tighter North American trade rules could add at least US$2 billion in annual costs for each Detroit automaker. A 50% Canadian rate could widen those cost differences on affected models unless the eventual policy preserves significant content-based relief.
Automakers Are Hedging, Not Simply Leaving Canada
The pressure has not produced a simple rush out of Canada. General Motors and Unifor reached a tentative agreement in August that called for about C$1.1 billion in Canadian investment. The package included C$144 million to add next-generation heavy-duty GMC Sierra production at Oshawa, a previously announced C$691 million commitment tied to new V8 engine production, and C$215 million for a new generation of transmissions in St. Catharines beginning later in the decade. GM also agreed not to immediately sell or close its CAMI plant in Ingersoll while alternative production is studied.
Ford’s Oakville Super Duty investment tells a similar story: companies still have billions tied up in Canadian facilities, tooling and workers even while trade policy is unstable. At the same time, there are warning signs. Stellantis has considered options for its Brampton plant after previously moving planned Jeep Compass production to Illinois. The mixed picture is more useful than a simple “stay or leave” narrative. Existing plants can remain strategically valuable while the next product allocation or expansion becomes much harder to approve without clearer trade rules.
January 1 Also Collides With Existing CUSMA Content Rules
January 1, 2027 already mattered to automotive compliance teams before Trump’s 50% threat. Under the existing CUSMA rules of origin, the regional-value requirement for certain passenger-vehicle and light-truck parts listed in the agreement’s automotive appendix is scheduled to rise on January 1. For those parts, the requirement moves from 54% to 60% under the net-cost method, or from 64% to 70% under the transaction-value method. That phase-in was written into the trade agreement years ago and is separate from the new tariff dispute.
The overlap creates an unusually awkward planning environment. Suppliers already needed to document more North American content for affected parts, while automakers are simultaneously trying to estimate whether Canadian-origin vehicles and components could face a much higher U.S. tariff. Those are two different policy mechanisms and should not be confused, but they hit many of the same sourcing and compliance teams. A supplier considering a new contract for 2027 now has to think about origin thresholds, customer location and potential tariff exposure at the same time.
The Deadline Is Serious, but the Outcome Is Still Negotiable
The deadline is serious, but it is not the same thing as a guaranteed outcome. Some auto-industry executives told Reuters they remained hopeful that Canada and the United States could reach an agreement before January, and several viewed the months between the announcement and the deadline as evidence that negotiations could still change the result. That uncertainty cuts both ways. A company that assumes the tariff will disappear could be exposed if it does not; a company that makes an expensive production shift too early could regret it if a deal is reached.
As of September 25, U.S. Trade Representative Jamieson Greer said Washington felt no urgency to strike a deal with Canada even as the broader dispute deepened. That makes the waiting game harder for manufacturers. The practical response is not to predict which government will move first, but to prepare multiple operating cases: one with the current tariff structure, one with a negotiated reduction, and one with the threatened 50% rate. January 1 is therefore functioning as a corporate decision point before it becomes a customs deadline.
What the Next Three Months Mean for Workers and Buyers
For workers and buyers, some effects could appear before January 1 if companies begin adjusting production schedules, inventory or sourcing in anticipation of the risk. Analysts have warned that some Canadian production lines could become uneconomic at a 50% tariff, while automakers are already evaluating how much tariff cost they can absorb and how much might eventually affect pricing. Honda said in August that it was not then passing tariff costs on to North American buyers, underscoring that higher border costs do not automatically translate into an immediate sticker-price increase.
The employment stakes are also broader than final assembly. Canada’s auto industry directly employed more than 125,000 people in 2024 and supported about 427,000 additional jobs, according to ISED. Statistics Canada later reported that employment in motor-vehicle parts manufacturing fell 9.3% during 2025, while motor-vehicle manufacturing employment declined 1.3%; those changes reflected multiple forces, including retooling and supply disruptions, not tariffs alone. With that backdrop, automakers are heading into the final months of 2026 planning for several possible versions of January rather than betting on only one.