





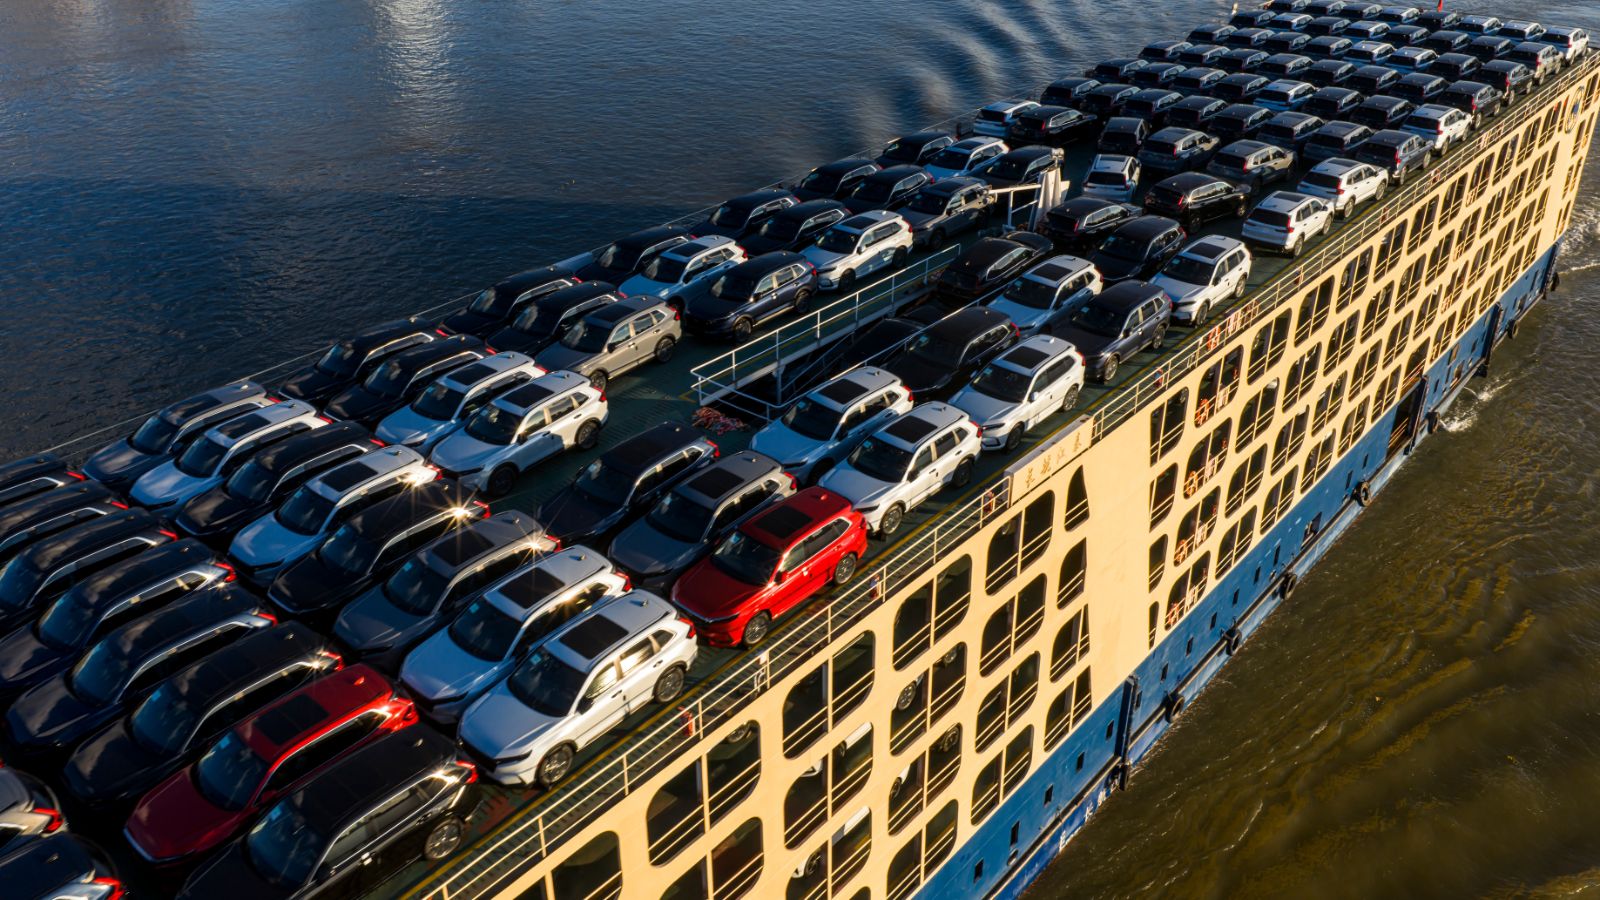
Europe’s auto market is reaching a point that would have seemed improbable only a few years ago. Chinese brands, led by companies such as BYD, MG and Chery, captured nearly 12% of European new-car sales in August 2026, according to Dataforce, setting another record as their international expansion accelerates. At the same time, Canada has begun allowing substantially more China-made electric vehicles into its market after replacing a 100% surtax with a controlled import quota.
The two markets are hardly identical, but their experiences are becoming increasingly connected. Europe shows how quickly Chinese automakers can build share when they have competitive products and broad market access. Canada is taking a more managed approach, balancing affordability, trade relations, domestic manufacturing and concerns about how greater competition could affect established automakers and workers.
Europe’s 12% Milestone Is Bigger Than One Strong Month
The headline number is striking because Chinese brands are no longer occupying a tiny corner of the European market. Dataforce figures reported in September showed manufacturers including BYD reaching nearly 12% of new-car sales across a region encompassing the European Union, EFTA markets and the United Kingdom during August. Demand for battery-powered and hybrid vehicles increased 27% during the month, helping lift the overall market by 4.6%. Chinese manufacturers were positioned particularly well to capture that growth because their portfolios increasingly cover several forms of electrification rather than relying entirely on battery-electric cars.
The pace of expansion also shows how quickly the competitive landscape has changed. In August 2025, JATO Dynamics put Chinese brands at only 5.5% of the European market, although differences in geographic coverage and methodology mean the two figures should not be treated as perfectly comparable. Even so, the direction is unmistakable. Chinese manufacturers have moved beyond being interesting newcomers displayed at auto shows. They are becoming recurring choices for ordinary European buyers shopping for compact SUVs, crossovers, hybrids and EVs.
Hybrids Are Doing Much of the Heavy Lifting
Battery-electric vehicles helped establish the reputation of China’s automotive industry, but hybrids have become one of its most effective tools for gaining European customers. Dataforce reported that Chinese brands accounted for roughly one-quarter of European hybrid sales in August and about one-third of plug-in hybrid sales. That matters because a plug-in hybrid can appeal to consumers who want lower fuel use and some electric driving without depending entirely on public charging infrastructure. It also gives manufacturers another price point between conventional gasoline vehicles and full EVs.
This product mix is especially important in markets where drivers remain concerned about charging availability or routinely travel long distances. Models such as the BYD Seal U, Jaecoo 7 and MG HS have already demonstrated how Chinese companies can use plug-in hybrids to compete in mainstream family-vehicle categories. The strategy is broader than simply selling inexpensive cars. Chinese manufacturers are offering different powertrains under the same brand umbrellas, allowing dealers to meet customers at several stages of the transition toward electrification rather than betting everything on immediate acceptance of battery-only vehicles.
Europe’s Tariffs Have Changed the Products China Sends
European trade policy has unintentionally created a sharp distinction between different Chinese powertrains. The European Commission imposed additional countervailing duties on China-made battery-electric cars after concluding its anti-subsidy investigation, with definitive company-specific rates including 17% for BYD, 18.8% for Geely and 35.3% for SAIC. Those duties were established for battery-electric vehicles, not hybrids, giving manufacturers a strong commercial reason to increase hybrid and plug-in hybrid exports while continuing to develop local production.
That gap is now attracting political attention. European officials have been discussing ways of responding to the rapid increase in Chinese hybrid imports, while China has opposed reports of potential voluntary export limits and argued that restrictions should comply with World Trade Organization rules. The dispute illustrates how quickly automotive trade measures can change corporate strategy. A tariff aimed specifically at one technology does not necessarily stop overseas expansion; it can instead encourage manufacturers to emphasize products outside the measure’s scope.
Britain and Germany Show Two Different Paths
The United Kingdom demonstrates what Chinese brands can achieve in a European market without the EU’s additional countervailing duties on China-made battery EVs. Dataforce figures reported in September indicated that more than one in five new cars sold in Britain came from Chinese brands. Names such as BYD, MG and Chery-owned Jaecoo have become increasingly visible on British roads, giving newcomers something every automotive brand ultimately needs: enough volume for consumers to encounter the vehicles routinely rather than viewing them as unusual imports.
Germany provides a different benchmark. Chinese manufacturers held approximately 6.4% of its market in August, considerably below the British share but still significant because Germany is Europe’s largest national auto market. That means even a single-digit percentage can translate into meaningful volume. The contrast also illustrates why a single “European” number can hide substantial variation. Consumer preferences, incentive programs, tariffs, dealership availability and domestic-brand loyalty differ enormously across the region, so Chinese manufacturers are expanding market by market rather than experiencing one uniform continental surge.
Chinese Automakers Are Becoming European Manufacturers
Importing cars is only one stage of China’s European strategy. Several manufacturers are increasingly attempting to build vehicles inside Europe, reducing exposure to tariffs while placing production closer to customers. BYD’s European adviser said in September that the company ultimately expects to need three vehicle assembly plants and one battery plant in Europe. Production has been starting at its Hungarian operation, while Spain and France have been among the locations examined for additional capacity.
GAC is pursuing a similar localization strategy. The manufacturer has said it intends to introduce 12 electric and hybrid models in France by 2030 and increase its French dealership network from around 50 locations in 2026 to approximately 200 by the end of the decade. It is also examining additional European manufacturing capacity. These moves complicate the traditional idea of competition between “European cars” and “Chinese cars.” If Chinese-owned manufacturers assemble vehicles locally, hire European workers and source increasing amounts of equipment locally, arguments about market access become intertwined with questions about investment, employment and where economic value is actually created.
China’s Domestic Slowdown Makes Overseas Growth More Important
European expansion is occurring while conditions inside China’s enormous car market have become much more difficult. Reuters reported in August that Chinese domestic vehicle sales had declined for 10 consecutive months through July, including a roughly 20% year-over-year drop that month. Exports, by contrast, were up sharply, reinforcing how international markets have become an increasingly important source of growth for manufacturers dealing with intense competition and weaker demand at home.
Individual manufacturers illustrate the shift. BYD’s overseas sales reached a record 189,466 vehicles in August, according to company figures compiled by CnEVPost, representing more than 40% of its monthly new-energy vehicle volume. Other manufacturers including Chery, Geely and Leapmotor are also building international operations. Export growth therefore should not be seen simply as a side project undertaken by companies already satisfied with their domestic positions. For many Chinese automakers, overseas expansion is becoming a central part of maintaining factory utilization, growing revenue and finding customers beyond a fiercely competitive home market.
Canada Has Replaced a Wall With a Controlled Gate
Canada’s position changed dramatically in less than two years. Ottawa introduced a 100% surtax on Chinese-made EVs in October 2024, on top of the existing 6.1% most-favoured-nation tariff. Beginning March 1, 2026, Canada removed that surtax for vehicles entering through a new country-specific quota. The first-year quota permits 49,000 qualifying China-origin EVs to enter at the 6.1% tariff, with the quota scheduled to increase by 6.5% annually.
The arrangement resulted from broader Canada-China negotiations that also addressed agricultural trade and other commercial disputes. Ottawa has presented the EV provision as managed market access rather than unrestricted liberalization and has said it hopes the framework can encourage Chinese joint-venture investment in Canada. Beijing, meanwhile, publicly welcomed the adjustment as improved market access for Chinese manufacturers. The result places Canada somewhere between Europe’s increasingly contested access model and the much tougher barriers Chinese manufacturers face in the United States.
The 49,000-Vehicle Limit Keeps the Opening Relatively Small
A quota of 49,000 vehicles sounds large until it is compared with the entire Canadian new-vehicle market. Canada recorded approximately 1.9 million new light-vehicle sales in 2025, according to DesRosiers Automotive Consultants data. Ottawa itself described the initial Chinese EV quota as representing less than 3% of annual Canadian new-vehicle sales. In other words, the policy can introduce meaningful competition without allowing Chinese manufacturers to capture anything resembling Europe’s current 12% share immediately.
The quota could nevertheless become important within the much smaller electric-vehicle segment. Allocation also matters because numerous companies may ultimately compete for limited import capacity. Canada initially operated the quota on a first-come, first-served basis and consulted manufacturers, importers, unions and other stakeholders on longer-term administration. Questions included whether access should be connected to Canadian investment, whether allocations could be transferred and whether unused allocations should be redistributed. That structure gives Ottawa considerable influence over which companies can turn theoretical market access into actual vehicles sitting in Canadian dealerships.
Affordability Is Built Into Canada’s Quota
One unusual element of Canada’s arrangement is that the quota is designed gradually to favour lower-priced vehicles. Government documents state that the share reserved for EVs with a free-on-board price of C$35,000 or less rises from 10% in the second year to 50% in the fifth year. The first-year access level of 49,000 vehicles also grows by 6.5% annually. That means the policy is not simply intended to make room for high-priced electric SUVs or luxury imports; it increasingly creates space for less expensive products as the system matures.
That could address one of the persistent challenges surrounding EV adoption: upfront purchase price. Chinese manufacturers have become particularly competitive in smaller cars and mass-market EVs, categories where North American choices remain thinner than in Europe or China. Whether international sticker prices translate directly into equally aggressive Canadian pricing is another matter. Freight, certification, dealer costs, parts inventories, warranty reserves, currency movements and the 6.1% tariff all matter. Still, reserving quota for affordable vehicles creates an incentive for importers to consider products below the premium end of the EV market.
Federal Rebates Still Put China-Made Cars at a Disadvantage
Lower tariffs do not automatically make Chinese-built EVs equal to every competitor in Canada. The federal Electric Vehicle Affordability Program offers incentives of up to C$5,000 on eligible battery-electric and fuel-cell vehicles, but for vehicles built outside Canada, eligibility is generally restricted to models manufactured in countries with which Canada has a free-trade agreement. Canada does not have a free-trade agreement with China.
That creates an unusual two-track policy. Canada is deliberately permitting a controlled quantity of China-made EVs at the normal tariff while withholding the federal consumer incentive available to qualifying vehicles from free-trade partners. A competitively priced Chinese model may therefore need to overcome a several-thousand-dollar incentive advantage enjoyed by an eligible rival. The distinction could shape which manufacturers enter and which models make economic sense to import. It also means that the eventual Canadian retail battle will depend on more than headline factory prices. Automakers will have to compete on the transaction price consumers actually face after tariffs, incentives, financing and dealer costs are considered.
Jobs, Dealers and Supply Chains Remain the Hardest Questions
Greater consumer choice does not remove concerns about industrial consequences. Unifor has strongly opposed increased access for China-owned EV manufacturers, arguing that imports without corresponding Canadian production could threaten assembly and parts jobs. The union’s position is particularly significant because it represents tens of thousands of Canadian automotive workers. Its concerns are claims about potential future effects rather than proof that the quota will cause those outcomes, but they illustrate why the policy has remained controversial within the Canadian auto sector.
Dealers face a different set of practical questions. The Canadian Automobile Dealers Association said after the quota announcement that significant details remained unclear, including how quota access would be managed and which manufacturers could use it. New brands also need service departments, trained technicians, replacement parts, warranty systems and resale-value confidence. Selling the first shipment is relatively easy compared with supporting thousands of vehicles for a decade. Europe’s experience shows that establishing a durable automotive brand requires far more than putting a competitively priced EV on a showroom floor.
Europe Offers Canada a Preview, Not a Blueprint
Europe demonstrates that Chinese automakers can gain substantial market share rapidly when competitive pricing, electrified powertrains and distribution networks come together. It also shows that policy rarely freezes competition in place. Duties on battery-electric cars encouraged greater attention to hybrids and European production, while established automakers have been forced to respond through new products, cost reductions and restructuring. Chinese manufacturers, meanwhile, are increasingly treating overseas factories and local supply chains as part of their long-term expansion rather than relying exclusively on exports.
Canada’s experiment starts from a different position. Its 49,000-vehicle quota is deliberately limited, federal incentives still disadvantage China-built EVs, and the country’s automotive manufacturing base is tightly integrated with the United States. Reuters has reported that Chinese manufacturers have nevertheless been exploring Canada as an entry market and potential testing ground for broader North American ambitions. Europe’s nearly 12% share therefore matters beyond Europe. It demonstrates how quickly unfamiliar brands can become serious competitors once consumers, dealers and regulators give them enough room to establish themselves.