




















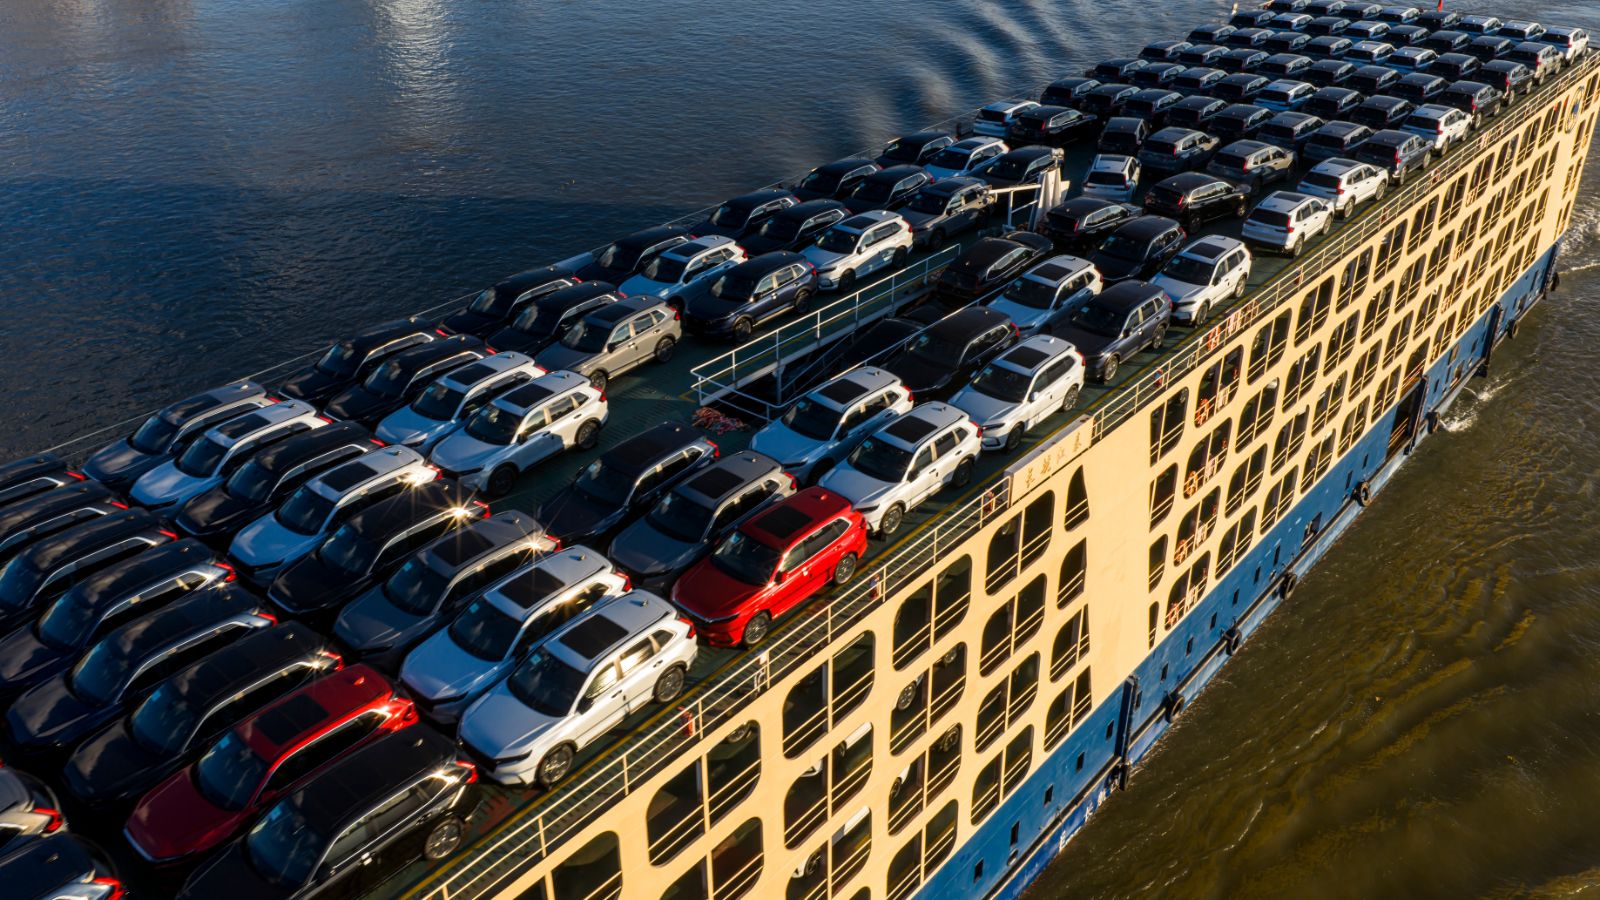
Europe’s auto dispute with China is moving into territory that looked largely untouched when Brussels imposed additional duties on Chinese-made battery-electric cars in 2024. The European Union is now reportedly asking Beijing to voluntarily restrain sales of Chinese-made hybrids to roughly 15% of the relevant European hybrid market, a sharp reduction from a share reported at more than one-third.
The proposal has not been formally adopted, and its exact design remains subject to negotiation. Yet the message from Brussels is increasingly difficult to miss. Hybrids have become a major route for Chinese automakers to expand in Europe, and EU policymakers are considering whether the trade protections created for fully electric vehicles left too large an opening elsewhere in the market.
Hybrids Have Become the New Trade Fault Line
The latest pressure emerged after the Financial Times reported that EU officials were seeking a voluntary Chinese commitment to restrict hybrid vehicle exports. Reuters subsequently reported the proposal, while noting that it could not independently verify the FT account and that the European Commission had not immediately confirmed it. That distinction matters: Europe has not enacted a 15% quota. It is attempting to negotiate one, with the possibility of stronger trade measures if talks fail.
The reported target would bring Chinese-made hybrids down from more than one-third of the relevant market to around 15%. The shift would be significant because hybrids have moved from the edges of the EU-China auto disagreement to its centre. What began as an anti-subsidy investigation focused specifically on battery-electric cars is becoming a broader argument about where Chinese production capacity can enter Europe, how quickly it can gain market share and how much protection European manufacturers should receive while restructuring their businesses.
The EV Tariff Gap Created a Powerful Incentive
Brussels finalized its countervailing duties on Chinese-built battery-electric vehicles in October 2024 after concluding that China’s BEV value chain benefited from subsidies that threatened injury to European producers. Depending on the manufacturer, additional duties currently range from 7.8% for Tesla’s Shanghai operation to 35.3% for SAIC, on top of the EU’s normal passenger-car import tariff. BYD faces an additional 17% duty and Geely 18.8%.
Hybrids were outside the original investigation. They generally continued to face the standard 10% EU passenger-car tariff rather than the much heavier effective rates placed on many Chinese-made BEVs. Trade flows responded dramatically. Reported EU imports of Chinese hybrids climbed from roughly 3,800 vehicles in October 2024 to around 50,000 in July 2026. That does not prove tariffs alone caused the surge—consumer demand and new model launches also matter—but it illustrates how quickly manufacturers can redirect products when one powertrain faces substantially higher barriers than another.
European Buyers Are Already Deep Into Hybrid Powertrains
Brussels is focusing on a segment that has become central to the European car market rather than a temporary technology with negligible sales. European Automobile Manufacturers’ Association data show conventional hybrid-electric vehicles accounted for 37.3% of EU new-car registrations during the first half of 2026. Plug-in hybrids held another 9.8%. Battery-electric cars captured 20.7%, while petrol and diesel combined had fallen to 29.7%.
Those figures explain why hybrids provide such a valuable path into Europe. Buyers who remain hesitant about relying exclusively on charging can still obtain an electrified vehicle while retaining a combustion engine for longer journeys. Plug-in hybrids add the prospect of electric commuting without requiring every trip to depend on charging infrastructure. Chinese manufacturers have built increasingly competitive products around that middle ground. For European policymakers, therefore, allowing rapid expansion in hybrids while heavily regulating Chinese BEVs risks moving competitive pressure from one powertrain category to another rather than resolving the underlying trade dispute.
Chinese Brands Have Turned Hybrids Into a Growth Engine
Chinese automakers are no longer peripheral players in Europe. Reuters analysis put Chinese brands at roughly 9% of EU car sales during the first half of 2026, compared with much smaller shares only a few years earlier. Wider European registration data have also shown particularly strong momentum for plug-in hybrids, giving manufacturers such as BYD, Chery and SAIC another route to customers beyond pure battery-electric cars.
The products themselves are increasingly visible in ordinary dealerships rather than confined to specialist EV showrooms. BYD’s Seal U DM-i, for example, has become an important part of the company’s European expansion, while Chery has been building its presence through brands such as Omoda and Jaecoo. Competitive prices, long equipment lists and rapid model launches have intensified pressure on established manufacturers. The trend also shows why regulating only BEVs was unlikely to freeze the competitive landscape. Chinese automakers have enormous domestic product portfolios and can alter the mix of battery-electric, plug-in hybrid and other electrified vehicles shipped abroad as market conditions change.
Brussels Is Framing the Fight Around Deindustrialization
European officials increasingly describe the dispute in industrial rather than purely environmental terms. The FT reported an EU official saying the objective of restricting Chinese hybrid exports was to stop deindustrialization. Germany’s Vice Chancellor and Finance Minister Lars Klingbeil has separately called for EU trade protections to be expanded to Chinese-made plug-in hybrids and for tighter local-content rules, arguing that European manufacturers face unfair competition.
The anxiety comes during an unusually painful restructuring of the continent’s auto sector. Volkswagen approved a transformation plan in September that involves another 50,000 job reductions, bringing agreed reductions across the group to roughly 100,000, while alternatives are being considered for four German plants. Chinese competition is only one factor: Volkswagen also faces U.S. tariffs, high costs, excess capacity and weaker performance in China. Still, the political stakes are substantial. ACEA estimates the broader European automotive sector supports about 13.2 million direct and indirect jobs, including roughly 2.4 million manufacturing positions. Even modest changes in production therefore reverberate well beyond assembly plants.
The Hybrid Demand Is Part of a Much Bigger China Negotiation
Cars are only one piece of a much larger attempt to rebalance EU-China commerce. The EU’s goods trade deficit with China reached €360.6 billion in 2025 and widened further during the first half of 2026. European officials have also raised concerns about Chinese exports of batteries, chemicals, plastics and other industrial goods, while European businesses continue to seek better access to the Chinese market.
The two sides established formal China-EU Trade and Investment Consultations in June, creating workstreams covering trade balancing, export controls, intellectual property and World Trade Organization reform. The calendar is now becoming important. Trade Commissioner Maroš Šefčovič has sought tangible progress by October, and he held a lengthy video discussion with Chinese Commerce Minister Wang Wentao on September 17. European officials said management of Chinese exports, EU access to the Chinese market and rare-earth export controls were discussed ahead of meetings scheduled in Beijing for October 8 and 9. The hybrid dispute is therefore being negotiated alongside much broader economic grievances.
Beijing Rejects Europe’s Overcapacity Diagnosis
China sees the dispute very differently. Its Commerce Ministry has repeatedly rejected European accusations of damaging industrial overcapacity, arguing that competitive Chinese exports are being treated as a political problem and warning that new discriminatory measures would amount to protectionism. Beijing has publicly called for disagreements to be resolved through consultation rather than unilateral restrictions and says China should be regarded as a partner in addressing Europe’s economic challenges rather than their source.
There is also a recent history showing how an automotive dispute can spread into unrelated industries. After the EU-China EV confrontation intensified, Beijing pursued trade-remedy cases affecting European brandy, pork and dairy products. China presented those measures as legitimate anti-dumping or anti-subsidy actions, while European officials challenged aspects of the cases and their justification. That experience raises the economic stakes of the hybrid negotiations. Additional European restrictions on Chinese cars would not necessarily produce retaliation, but companies in sectors far removed from automobiles have reason to watch the talks carefully.
Local European Production Could Redraw the Battle Lines
Trade barriers are also encouraging Chinese companies to become more European in how they manufacture. BYD is beginning production at its first European passenger-vehicle factory in Hungary and has said it will eventually need three assembly plants and a battery factory in the region. Its European adviser has indicated the company is examining existing facilities in countries including Spain and France for another site. Chery, Leapmotor, Dongfeng and Geely are also pursuing various European manufacturing or partnership strategies.
That creates a more complicated long-term question than simply deciding how many Chinese-branded cars Europe will accept. If future restrictions are based principally on where a vehicle is manufactured, local production could materially change Chinese automakers’ exposure to import measures. If Brussels instead places greater weight on component sourcing, subsidies or local-content thresholds, assembling vehicles inside Europe may not settle the issue. No final hybrid regime has been published, so those details remain unresolved. What is already clear is that Europe’s auto confrontation with China is evolving from a dispute about imported EVs into a broader contest over investment, factories, supply chains and who gets to manufacture the next generation of cars sold on European roads.