


A million vehicles leaving one country in a month is enough to reshape the conversation about who builds the world’s cars. Newly released Chinese customs figures show that exports of automobiles, including chassis, reached approximately 1.1 million units in October 2026. The surge is arriving as Chinese manufacturers expand abroad and domestic demand weakens.
For Canada, the question is no longer whether Chinese vehicles can compete internationally. It is how Canadian assembly plants, parts suppliers and dealerships respond when lower-priced electric models enter a market already dealing with U.S. tariffs, uncertain investment decisions and families watching the cost of a new car. The opportunities for buyers and the risks for workers are becoming harder to separate.
One Month, More Than a Million Exports
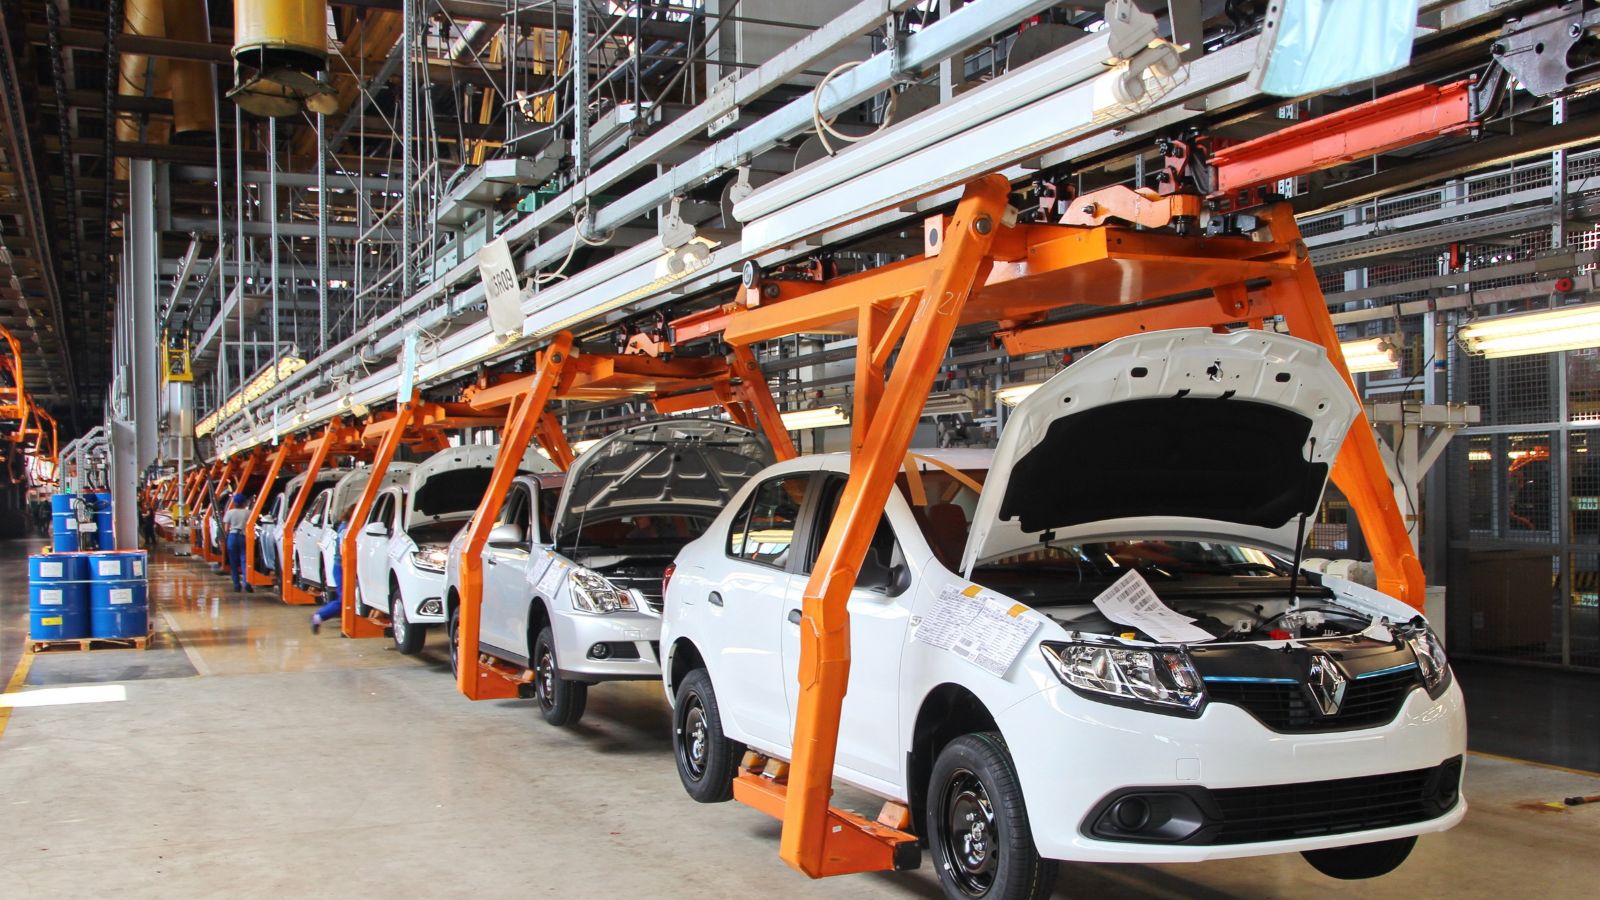
China’s General Administration of Customs reported exports of 1.108 million automobiles, including chassis, in October 2026. That was about 33.9% more than a year earlier. The scale fills carrier ships and keeps ports busy for weeks. The customs category is broader than passenger cars alone, an important distinction when comparing it with other industry releases.
The scale is especially revealing beside Canada’s own production. Canadian plants built more than 1.2 million vehicles during all of 2025, according to federal industry figures. China therefore sent abroad in one month a volume approaching what Canada assembled in an entire year. That is not a direct measure of competition inside Canadian dealerships: the Chinese shipments went to many countries, and Canada’s figures track production rather than exports. Still, the comparison shows the size of the manufacturing challenge facing a smaller, export-dependent country already navigating disrupted North American trade and uncertain long-term assembly investments.
The Ten-Month Total Shows This Is No One-Off
October’s impressive export figure reflected a wider surge throughout 2026. Chinese customs statistics put vehicle exports, including chassis, at approximately 9.736 million units during the first ten months of 2026, up 49.6% year over year. The reported value of those exports reached roughly US$169.5 billion. In other words, the story is not simply about inexpensive cars. China is also exporting enormous value through a rapidly expanding automotive business.
There is an important qualification. October’s 1.108 million customs count was below September’s approximately 1.182 million, so the upward trend has not been a straight line every month. Seasonal shipping patterns, changing incentives and tariff deadlines can influence when vehicles leave a port. For Canadian manufacturers trying to forecast the next several years, the longer-term volume matters more than one monthly jump. The numbers suggest Chinese companies have built an export operation too large for competitors to dismiss as a temporary experiment.
Electrified Vehicles Are Driving the Growth
Passenger-car data show how quickly electrification is changing exports. The China Passenger Car Association reported 928,000 passenger-vehicle exports in October, including 582,000 new-energy models. Those electrified vehicles represented 62.8% of the association’s passenger export total, and their shipments were up 144.7% from October 2025. This category includes battery-electric vehicles and plug-in hybrids, which appeal to different drivers.
These figures should not be confused with the customs total of roughly 1.1 million. The industry association’s passenger-vehicle measure has a different scope from customs data covering automobiles and chassis. But the direction is unmistakable: electrified models are taking up a much larger share of Chinese manufacturers’ overseas business. For established brands selling in Canada, that changes the competitive conversation. A new rival may offer not just a lower purchase price, but different battery technology, connected features and plug-in choices designed for motorists who are not ready to rely entirely on public charging.
Falling Home Sales Are Increasing the Pressure to Export
China’s overseas push coincides with a weaker domestic market. According to the passenger-car association, retail sales in October fell 27.1% from a year earlier to about 1.643 million vehicles. Sales of new-energy passenger cars declined 13.7%, even as they represented a record 67.5% of domestic passenger-car retail purchases. Traditional fuel-powered models fell more sharply, highlighting how consumer preferences have shifted within China itself.
For an automaker running large factories, slowing sales at home create a difficult choice: reduce output, cut prices or find customers elsewhere. Export markets offer another route, although they come with unfamiliar safety rules, dealerships and political resistance. The resulting pressure can reach Canadian consumers indirectly even before a Chinese badge appears on a nearby lot. Manufacturers watch competing prices abroad, then decide which models and investments deserve priority. China’s domestic slowdown therefore has consequences far beyond its borders, including throughout North America’s integrated automotive manufacturing networks.
The Export Race Has Multiple Major Players
Chinese vehicle exports are not one company’s achievement. In the passenger-car association’s October ranking, Chery shipped about 196,700 passenger vehicles abroad, followed by BYD at approximately 164,700 and Geely at 106,600. Their products cover different price points and powertrains, allowing manufacturers to compete across markets and price brackets rather than relying on electric city cars.
The picture is also more complicated than a simple contest between Chinese and established Western brands. Tesla’s Shanghai operations exported about 59,000 passenger vehicles in October, demonstrating that cars built in China are not necessarily sold by Chinese-owned companies. This distinction matters when discussing trade restrictions, which often depend on where a vehicle originates rather than the nationality of its badge. For Canadian dealers and parts businesses, the change brings both threats and possibilities: new brands can compete for sales, while overseas production networks can also create demand for logistics, retail services and specialized components.
China’s Cost Advantage Is Hard to Ignore
The International Energy Agency estimates that 70% of battery-electric cars sold in China in 2025 were cheaper than the average conventional car. Its research also shows that battery-pack prices in China were about 30% below those in North America. Intense competition, enormous domestic production scale and deeply connected supply chains have helped Chinese manufacturers reach price levels that remain difficult for many overseas producers to match.
A Canadian sticker price, however, will never be a simple conversion of a Chinese factory price. Shipping, import duties, currency movements, safety certification, dealer expenses and warranty support all add costs. Winter performance and service access can matter as much as price. This is why the potential competitive impact is significant but not automatic. An affordable electric crossover could appeal to a commuter worried about monthly payments, yet buyers will still compare financing, charging convenience, resale expectations and long-term reliability before making a decision.
Canada’s Policy Shift Has Opened a Limited Door
Canada’s approach to China-made EVs changed in 2026. After imposing a 100% surtax in 2024, Ottawa removed that surtax effective March 1 and introduced an initial annual quota of 49,000 Chinese EVs at the standard 6.1% tariff. Import permits are required, and the quota limits how many covered vehicles can enter. It is a tightly controlled market opening rather than unrestricted access to the Canadian market.
The federal government says the allocation represents less than 3% of Canada’s new-vehicle market. The quota is scheduled to grow by 6.5% annually, while the share reserved for lower-priced models is meant to increase over time. Ottawa’s affordability threshold refers to an import price of C$35,000 or less, not necessarily the final showroom price. That distinction matters to families expecting a bargain. It also matters to domestic manufacturers: policymakers are trying to introduce competition gradually while giving Canadian plants and suppliers room to adapt.
The Stakes Reach Well Beyond Auto Showrooms
Canada’s auto industry is an employment network, not just assembly lines. Federal figures show that the sector supported more than 121,000 direct Canadian manufacturing jobs and produced over 1.2 million vehicles in 2025. Its major assemblers include Ford, General Motors, Honda, Stellantis and Toyota, alongside hundreds of parts suppliers. A plant’s vehicle program sustains nearby tooling shops, fabricators and trucking companies.
The industry’s reliance on the United States adds another vulnerability. More than 90% of Canadian-made vehicles are exported south of the border, while Statistics Canada estimates that U.S. demand accounted for 76.4% of automobile and light-duty vehicle manufacturing jobs in 2024. Chinese imports into Canada do not automatically displace Canadian factory output, much of which is shipped abroad. But growing global competition, U.S. tariffs and model-allocation decisions can interact. That is why a new entrant’s success in Canadian dealerships matters to workers whose livelihoods depend on future production investments.
Canadian Buyers See Both Appeal and Risks
Canadian shoppers have mixed views on Chinese electric vehicles. J.D. Power’s 2026 Canadian EV consideration study found that 34% of new-vehicle shoppers were open to buying an EV, up from 28% in 2025. Among respondents considering an electric vehicle, 56% said they were open to a Chinese brand. Price and technology attract attention but cannot settle final purchase decisions.
The same research identified concerns over quality, security, parts availability and dealership networks. Cold-weather driving range and access to charging remain major obstacles for shoppers considering an EV. Canadian consumers also need to read incentive rules carefully: the federal Electric Vehicle Affordability Program generally requires eligible vehicles to be made in Canada or countries with which Canada has a free-trade agreement. China-built vehicles therefore do not qualify simply because they enter under the new import quota. Competitive pricing will matter, but consumer confidence after the sale may matter just as much.
The Bigger Test Is What Canada Builds Next
Ottawa’s response goes beyond import limits. Its February 2026 automotive strategy allocated $3 billion from the Strategic Response Fund and up to $100 million from a regional tariff initiative to support adaptation and investment. The government also introduced an EV affordability program and proposed further charging infrastructure support. The measures aim to attract vehicle and component production amid growing competition.
The China arrangement carries a second ambition: federal officials expect it to encourage joint ventures and new investment in Canadian electric-vehicle supply chains. Expectations, however, are not the same as signed factory commitments or new jobs. The meaningful test will be whether Canada secures production mandates, develops suppliers and delivers vehicles that local shoppers can afford. China’s exports show how quickly the market moves. The answer for Canada will depend less on keeping every competitor out than on ensuring Canadians help design, manufacture and service the vehicles of the future.