
Canada’s automotive market delivered another surprising performance in October 2026, with new-vehicle sales climbing despite trade disputes, higher borrowing costs, and growing pressure on household budgets. According to DesRosiers Automotive Consultants, approximately 162,000 new light vehicles were sold nationwide, representing a 1.8% increase compared with October 2025. The result marked the fifth consecutive month of year-over-year sales growth and brought the market within striking distance of its strongest October on record.
The improvement comes at a complicated time for Canada’s automotive industry. U.S. tariffs continue to create uncertainty for manufacturers, while inflation and higher interest rates make vehicle ownership more expensive. Yet Canadian consumers are still purchasing new cars, trucks, and SUVs in substantial numbers. Behind the encouraging figures, however, the industry faces important questions about affordability, consumer confidence, and whether the recovery can continue into 2027.
October’s Sales Increase Provides a Welcome Surprise
DesRosiers Automotive Consultants estimated that Canadian dealerships sold approximately 162,000 new light vehicles in October 2026, compared with roughly 159,000 during the same month last year. The increase of 1.8% translates into approximately 3,000 additional vehicles sold. Although that might seem like a relatively modest improvement, it represents a meaningful achievement for an industry navigating economic uncertainty. Dealerships have been dealing with unpredictable trade policies, shifting consumer expectations, and concerns about the future cost of vehicle ownership.
There is, however, an important detail behind October’s performance. The month included one additional selling day compared with October 2025, providing dealerships with more time to complete transactions. That calendar advantage helped support the monthly total, meaning the headline increase should not automatically be interpreted as a similar improvement in the daily sales pace. Nevertheless, the result demonstrates that purchasing activity has remained resilient. For dealerships that depend on consistent customer traffic and vehicle deliveries, maintaining positive sales momentum is encouraging even when the broader economic environment remains unsettled.
Five Consecutive Months of Growth Reverse an Earlier Slump
October’s performance becomes more significant when viewed against the difficult start to 2026. According to DesRosiers, Canada’s automotive market experienced eight consecutive months of year-over-year declines through May. By the end of that month, cumulative vehicle sales were running 3.7% below the comparable period in 2025. The situation raised concerns that economic uncertainty and higher ownership costs could produce a prolonged slowdown in consumer demand. Instead, the market began recovering during the summer and continued improving through the fall.
September had already delivered an encouraging result, with an estimated 168,000 vehicles sold, representing a 3.4% increase from the previous year. October extended the positive streak to five months and narrowed the year-to-date decline to just 0.5%. That improvement is substantial considering where the industry stood in May. It also illustrates why individual monthly results can sometimes provide a misleading picture of the wider market. Canadian buyers have not returned to purchasing vehicles at uniformly strong rates, but the sustained recovery suggests the industry has regained much of the momentum lost during the first part of the year.
October Comes Remarkably Close to an All-Time Record
One of the more impressive aspects of October’s results is how close sales came to a historical milestone. DesRosiers reported that the approximately 162,000 vehicles sold were only about 3,000 units below the strongest October on record, established in 2017. That places October 2026 among the strongest performances for the month, despite a considerably more complicated economic environment. For an industry facing tariffs, elevated fuel costs, and cautious consumers, approaching a monthly record is a notable accomplishment.
The seasonally adjusted annualized sales rate, commonly called SAAR, also improved to approximately 1.98 million vehicles, its highest level since February. September’s comparable rate had been 1.91 million. SAAR adjusts for recurring seasonal patterns and expresses the month’s sales pace as an annualized figure. It does not mean Canada is guaranteed to sell 1.98 million vehicles in 2026. Instead, it offers another indication of the market’s underlying strength during October. The combination of a near-record monthly total and an improving annualized rate suggests that demand has held up better than some economic indicators might imply, although it remains too early to declare a lasting recovery.
Trump’s Tariffs Continue to Threaten Automotive Stability
Strong dealership sales do not mean Canada’s trade problems with the United States have disappeared. The automotive industry remains particularly vulnerable because vehicles and components frequently cross the Canada-U.S. border during manufacturing. The U.S. continues to maintain a 25% sectoral tariff on automobiles and trucks, although qualifying vehicles receive an exemption for their U.S.-origin content, while CUSMA-compliant automotive parts have different treatment. These distinctions matter because tariff exposure varies considerably depending on a vehicle’s origin, components, and compliance with trade rules.
The Parliamentary Budget Officer’s October assessment illustrates the broader economic danger. It estimated that recent trade measures increased the trade-weighted average effective U.S. tariff rate on Canadian imports from 5.3% to 7.7%. It also projected that trade restrictions introduced since early 2025 could reduce Canada’s real GDP by 1.4% after five years compared with a pre-tariff baseline. Those figures are economy-wide estimates, not vehicle-specific tariffs. Still, they demonstrate why automotive manufacturers and suppliers remain concerned. Higher trade costs can squeeze profitability, complicate production planning, and discourage investment. October’s sales increase offers reassurance about domestic demand, but it cannot eliminate the challenges facing Canada’s automotive manufacturing network.
Higher Interest Rates Keep Affordability Under Pressure
Vehicle affordability remains one of the biggest obstacles facing Canadian consumers. On October 28, the Bank of Canada increased its benchmark overnight interest rate by 25 basis points to 2.5%, responding to persistent inflationary pressures. The decision came as Canadians were already dealing with elevated transportation costs. Statistics Canada’s September Consumer Price Index showed annual inflation of 3.1%, while gasoline prices were 27.8% higher than a year earlier. Those expenses can significantly influence how much households are comfortable spending on a vehicle.
There have been some improvements in automotive pricing. AutoTrader’s third-quarter 2026 Price Index indicated that new-vehicle prices declined by nearly 2% from a year earlier, while average new-vehicle monthly payments fell 3.7% to approximately $914. That reduction provides some relief, but a payment approaching $1,000 remains a substantial commitment, especially after accounting for insurance, fuel, maintenance, and other operating expenses. Higher policy rates can also create additional borrowing pressure, depending on lenders’ financing offers and when buyers secure their loans. For many households, the decision is no longer simply about choosing a preferred vehicle. It involves determining whether the total cost fits comfortably within an already stretched monthly budget.
Canada’s Weakening Job Market Adds Another Concern
October’s vehicle sales growth also stands in contrast to developments in the Canadian labour market. Statistics Canada reported that employment declined by approximately 4,700 positions during October, while the national unemployment rate increased to 6.7%. Private-sector employment fell by 53,000, although that decline was largely offset by an increase of 50,000 public-sector employees. The unemployment rate among Canadians aged 15 to 24 reached 13.7%, highlighting the particular difficulties facing younger workers seeking stable employment.
These figures matter because purchasing a vehicle often involves a financial commitment lasting several years. Households concerned about layoffs, reduced working hours, or uncertain income may be reluctant to take on additional debt. The Bank of Canada’s third-quarter consumer expectations research showed that spending intentions remained weak, with high prices and economic uncertainty continuing to discourage major purchases. That helps explain an apparent contradiction: Canadians can continue buying substantial numbers of vehicles even while consumer confidence remains fragile. Some purchases are necessary replacements, while others may involve financially secure households less exposed to employment uncertainty. October’s sales results therefore demonstrate resilience, but they should not be interpreted as evidence that the financial pressures affecting Canadian families have disappeared.
Toyota and Subaru Stand Out as Automakers Deliver Mixed Results
The national sales increase concealed substantial differences between individual manufacturers. Toyota Canada reported 26,219 vehicle sales in October, an improvement of 15.6% compared with the previous year. Its Toyota division delivered 23,088 vehicles, while Lexus achieved 3,131 sales, representing a 30.2% increase. Subaru posted an even more dramatic result, selling 9,198 vehicles nationwide. That represented a 69.6% year-over-year increase and established a new all-time monthly sales record for Subaru Canada, surpassing its previous record of 8,711 vehicles.
Not every manufacturer experienced comparable growth. Mazda Canada reported 6,446 October sales, down 5.4% from October 2025. Its year-to-date sales were also 11.6% lower, despite some individual SUVs performing well. Hyundai and Kia combined recorded more modest October growth of 2.4%, according to compiled monthly industry figures. These differences demonstrate that a recovering national market does not necessarily benefit every automaker equally. Product availability, model changes, consumer preferences, and pricing can all influence results. For dealerships, the distinction is important: a strong Canadian sales month might produce record deliveries for one brand while leaving another struggling to match its previous year’s performance.
Popular SUVs Lead Sales, but Smaller Cars Show Strength Too
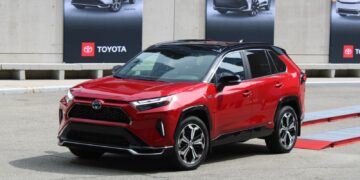
Canadian buyers continued showing substantial interest in established crossover and SUV nameplates during October. Among manufacturers reporting monthly model figures, the Toyota RAV4 recorded approximately 7,888 sales, an increase of 25.7% compared with October 2025. The Honda CR-V also delivered a strong performance, with approximately 5,539 units sold, up 26%. Subaru’s Crosstrek recorded around 3,797 sales, a remarkable 89.1% improvement. These models represent different approaches to practical family transportation but share an emphasis on everyday usability.
Interestingly, conventional passenger cars also delivered notable improvements. The Honda Civic recorded approximately 3,248 October sales, increasing 43.7% from the previous year, while Toyota Corolla sales climbed 41.1% to approximately 2,889 units. Hyundai’s Elantra also registered significant growth in the available monthly data. These results suggest that the market’s strength was not confined to larger SUVs. For buyers concerned about purchase prices, fuel consumption, and daily commuting expenses, compact cars remain relevant alternatives. However, the figures cover models with available monthly reporting and should not be interpreted as a complete ranking of every vehicle sold in Canada. They nevertheless illustrate the varied purchasing decisions supporting October’s overall sales improvement.
Hybrids and Electric Vehicles Are Reshaping the Market
Electrified vehicles provided another important source of momentum during October. Toyota Canada reported a record 17,735 electrified vehicle sales, representing 67.6% of its total monthly deliveries and a 70.2% increase from October 2025. The company also reported 6,195 sales of the Canadian-assembled RAV4 Hybrid. These figures highlight growing interest in vehicles offering alternatives to conventional gasoline-only powertrains. Importantly, Toyota’s electrified category includes conventional hybrids as well as plug-in hybrids and battery-electric vehicles, so the entire total should not be interpreted as electric-only sales.
Canada’s broader zero-emission vehicle market has also been improving. The latest available official monthly figures from Statistics Canada showed 22,716 zero-emission vehicles sold in August, up 55.1% from August 2025 and accounting for 13% of total sales that month. That category includes battery-electric and plug-in hybrid vehicles, but excludes conventional hybrids. DesRosiers described October’s zero-emission market as strong without identifying widespread evidence of purchases being accelerated ahead of declining year-end incentives. This distinction matters because changes in government rebates can affect buying decisions. The federal Electric Vehicle Affordability Program currently offers eligible battery-electric buyers up to $5,000, scheduled to decline to $4,000 in 2027, making incentives another factor worth watching.
Tariff Fears Could Influence Purchases Before the End of 2026
Although October delivered encouraging results, the final two months of 2026 will help determine whether Canada’s automotive recovery can be sustained. DesRosiers estimated that cumulative sales were just 0.5% below the comparable 2025 period at the end of October, a considerable improvement from the 3.7% decline recorded at the end of May. Closing that remaining gap would represent a meaningful turnaround. Nevertheless, the market still faces uncertainty surrounding trade negotiations, borrowing costs, and whether consumers will continue making major purchases.
Recent consumer research suggests that expectations about future prices could influence near-term buying decisions. AutoTrader reported that 81% of surveyed shoppers planning to purchase a vehicle within six months wanted to buy before January, while 85% expected new-vehicle prices to increase because of trade uncertainty. Those findings reflect the views of prospective buyers, not a prediction that prices will necessarily rise. They also raise an important question: could some purchases scheduled for 2027 be moving into the final months of 2026? The answer may become clearer as year-end results emerge. For now, October has demonstrated that Canadian automotive demand remains resilient, even as the economic conditions supporting future sales remain uncertain.