





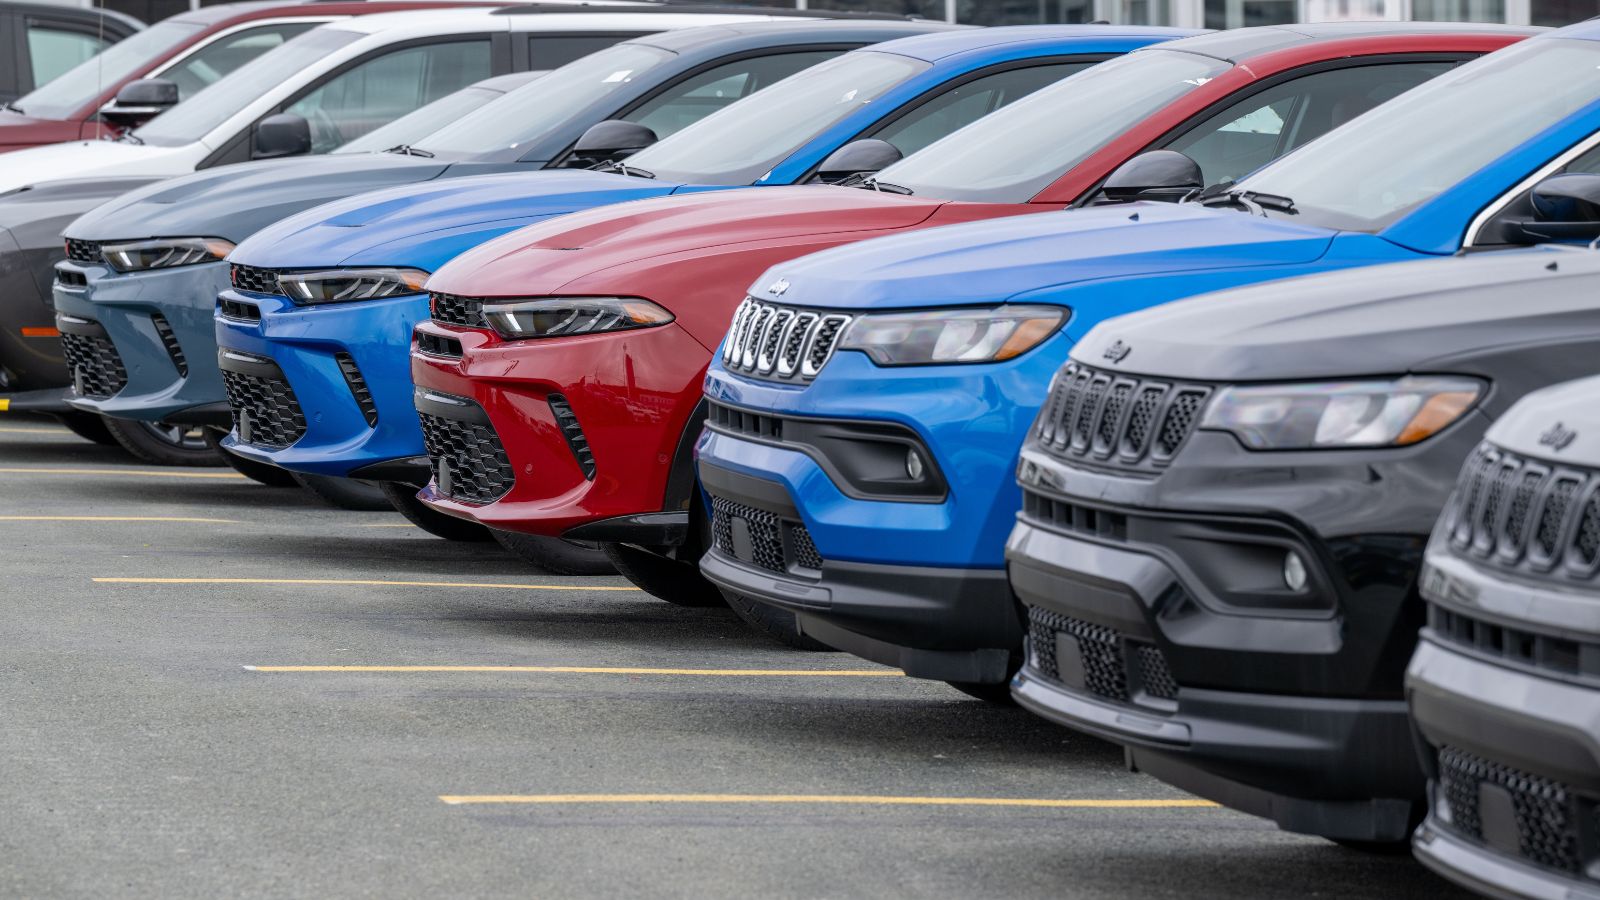
Canada’s new-vehicle market is finally putting together something that looked difficult to imagine earlier in 2026: a sustained run of growth. An estimated 168,000 new light vehicles were sold in September, 3.4% more than a year earlier and enough to extend the market’s year-over-year winning streak to four months.
The recovery, however, comes with an important qualification. Sales through September remained 0.7% below the same period in 2025. In other words, summer and early-fall demand has repaired much of the damage from a weak start to the year without completely erasing it. With household budgets still strained by vehicle costs, elevated gasoline prices and broader economic uncertainty, the final three months of 2026 will determine whether the market merely stabilized or managed to finish the year back in positive territory.
Four Consecutive Gains Have Changed the Tone
The turnaround did not happen in a single strong month. June ended an eight-month run of year-over-year declines when DesRosiers Automotive Consultants estimated roughly 182,000 new light vehicles were sold, a 1.9% increase from June 2025. July followed with approximately 173,000 sales, up a modest 0.5%. August produced the biggest gain of the streak, climbing 5.4% to roughly 168,000 vehicles before September added another 3.4% increase.
That progression matters because it makes the rebound harder to dismiss as a one-month statistical quirk. There have still been calendar effects to consider: both June and September had an additional selling day compared with the equivalent months a year earlier. Even so, four consecutive positive comparisons represent a clear improvement from the first half of 2026. For dealerships that spent the spring dealing with softer demand and economic uncertainty, the difference between repeated declines and four months of growth can meaningfully change inventory planning, marketing and expectations heading into the holiday period.
The First Half Left a Deficit That Has Not Completely Disappeared
Canada entered the summer with considerable ground to recover. DesRosiers estimated that approximately 950,000 new light vehicles were sold during the first six months of 2026, down 2.6% from roughly 976,000 during the same period in 2025. That weakness helps explain why four consecutive months of improvement have still not been enough to put the full year ahead.
The gap has narrowed significantly. Through August, approximately 1.29 million vehicles had been sold, leaving the market about 1.2% behind the previous year. September reduced the year-to-date deficit further to just 0.7%. That is a much healthier position than the market faced at midyear, but it also illustrates the difference between improving momentum and outright recovery. A dealership can be busier than it was last September while the industry as a whole remains below last year’s cumulative sales total. The final result for 2026 therefore depends heavily on whether the summer rebound can survive tougher comparisons during the fourth quarter.
The Annualized Sales Pace Points to Stability Rather Than a Boom
Another useful measure is the seasonally adjusted annual rate, or SAAR, which adjusts monthly results for seasonal patterns and translates them into an annualized pace. September’s SAAR came in around 1.91 million vehicles. That was above August’s roughly 1.86-million pace and June’s approximately 1.84 million, but it remains better interpreted as stabilization than as the beginning of a dramatic sales surge.
The distinction becomes clearer when looking at the raw numbers. Both August and September generated estimates of approximately 168,000 sales, yet the annualized rate moved because the months have different calendars and seasonal characteristics. DesRosiers has described the market as remarkably stable despite significant economic and trade uncertainty. That may actually be the most important development of the summer. Canadian vehicle demand is no longer falling month after month, but neither is it racing far beyond recent norms. For manufacturers and dealers, a predictable market near the 1.9-million annualized level can be more manageable than the volatile swings that characterized parts of the previous several years.
Toyota Shows Where Some of the Growth Is Coming From
Toyota Canada provided one of the clearest examples of a manufacturer outperforming the overall market during the third quarter. Toyota Canada Inc. sold 70,008 vehicles during Q3, an 8.3% increase from a year earlier. September was even stronger, with 22,477 Toyota and Lexus vehicles sold, up 13.6%, setting monthly and quarterly records for the company.
Electrified models were central to that performance. Toyota Canada reported 15,077 electrified-vehicle sales in September, up 49.8% year over year and representing 67.1% of the company’s total monthly volume. Through the first nine months of 2026, Toyota Canada had already sold 130,369 electrified vehicles, exceeding the 123,879 it sold during all of 2025. The numbers reinforce an important shift in the Canadian market: growth does not necessarily mean buyers are returning uniformly to traditional gasoline vehicles. Hybrids, plug-in hybrids and battery-electric models are becoming increasingly important parts of the sales mix, particularly for manufacturers with broad electrified lineups.
Not Every Automaker Is Sharing in the Recovery
A growing national market can hide large differences between individual brands. Nissan Group Canada, for example, reported third-quarter sales of 22,496 vehicles, down 17% from the same quarter in 2025. Through September, Nissan and Infiniti combined had sold 74,417 vehicles, nearly 15% fewer than during the first nine months of the previous year. The company still saw growth from individual products such as Kicks and Rogue, but that was not enough to offset broader declines.
Mazda also illustrates the uneven nature of the market. Mazda Canada sold 6,454 vehicles in September, a 19.3% year-over-year decline, while its year-to-date sales of 56,148 vehicles were down 12.3%. Yet even within those weaker totals, several SUVs performed well. CX-5 sales were up 4.5% through September, while CX-90 sales gained 11.6%. Those contrasting results show why the national 3.4% increase should not be read as evidence that every showroom suddenly became busier. Buyers continue to concentrate around specific brands, powertrains and vehicle types.
Affordability Remains the Market’s Biggest Constraint
The recent sales gains have occurred despite an affordability problem that has not disappeared. Industry analysis from Canadian Black Book cited by Canadian Auto Dealer puts the average vehicle sold in Canada in roughly the $60,000-to-$65,000 range. AutoTrader’s 2026 market research has similarly described affordability as a major concern even as vehicle pricing began to moderate somewhat during the year.
The wider economy gives buyers additional reasons to be cautious. The Bank of Canada held its policy rate at 2.25% in September, but financing costs are only one piece of a household’s vehicle budget. Statistics Canada reported that gasoline prices were 22.8% higher in August than a year earlier. Employment also declined by 42,000 during August while the national unemployment rate remained at 6.4%. None of those figures alone determines whether a family buys a new SUV or keeps an existing vehicle another year, but together they explain why the market’s recovery has been gradual. Buyers may be returning, yet monthly payments, fuel costs, insurance and other ownership expenses continue to matter heavily.
Electrified Vehicles Are Becoming Harder to Separate From the Main Market
Electric and electrified vehicles are increasingly part of the broader Canadian sales story rather than a separate niche. Statistics Canada reported 21,876 new zero-emission vehicles sold in June, a 56.1% increase from June 2025. ZEVs represented 11.5% of all new motor vehicles sold that month, compared with 7.9% a year earlier. July produced another 18,920 ZEV sales, up 36%, lifting the category to 10.7% of the market versus 7.7% in July 2025.
Those figures include battery-electric and plug-in hybrid vehicles and show substantial year-over-year growth, even though performance varies considerably by manufacturer and model. Toyota’s results demonstrate how conventional hybrids are also reshaping the market. Its broader electrified lineup represented more than two-thirds of Toyota Canada’s September volume, while the company also reported a record 10,114 battery-electric and plug-in hybrid sales during the third quarter. For Canadian buyers, electrification is increasingly less about choosing between an EV and a gasoline vehicle and more about selecting among several different powertrain options.
The Fourth Quarter Will Decide How Strong This Recovery Really Is
September leaves the Canadian auto market in a much better position than it occupied during the spring. Four consecutive monthly gains have reduced the year-to-date sales shortfall from 2.6% at the end of June to just 0.7% through September. The market has also maintained an annualized sales pace close to 1.9 million vehicles, while manufacturers such as Toyota have demonstrated that substantial growth is still possible within specific parts of the industry.
The final three months may be more difficult. DesRosiers has cautioned that fourth-quarter comparisons could become tougher because sales were comparatively strong late in 2025. At the same time, Canadian consumers remain exposed to high vehicle costs, fuel-price pressure and uncertainty surrounding cross-border trade. That makes the current streak encouraging without making the year’s outcome inevitable. September confirms that demand has stabilized and that Canadian buyers are still willing to enter showrooms when the product, price and financing align. Whether that is enough to erase the remaining 0.7% deficit will be the key question as 2026 enters its final stretch.