






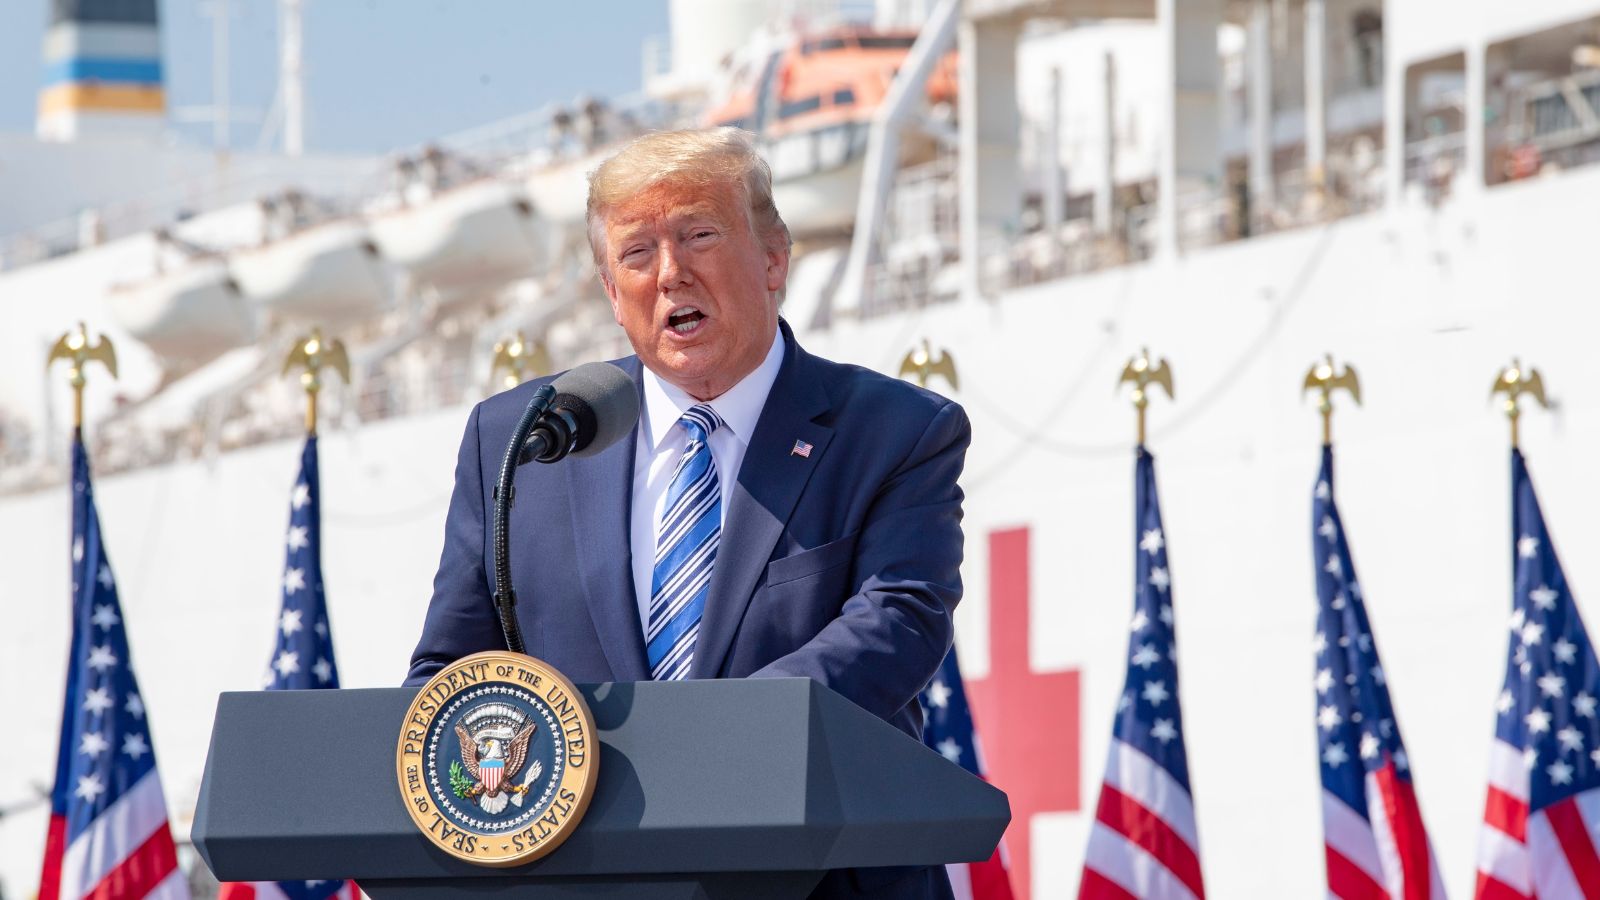
Two deeply integrated auto markets are starting to pull in different regulatory directions. On September 26, President Donald Trump said he had approved new U.S. fuel-economy standards, advancing a rollback of the Biden-era Corporate Average Fuel Economy trajectory. The precise final targets were not included in his announcement, so the last publicly detailed NHTSA proposal remains the clearest numerical guide: roughly 34.5 mpg fleetwide in model year 2031, compared with about 50.4 mpg under the 2024 rule.
Canada, meanwhile, is preparing stronger, Canada-specific greenhouse-gas standards for model years 2027–32 while moving to repeal its existing EV sales mandate. Ottawa says the new approach should remain technology-neutral in the early years while putting the country on a path toward 75% EV sales by 2035 and 90% by 2040. The result is an increasingly important regulatory split inside one tightly connected North American auto industry.
Approval Announced, but the Final U.S. Numbers Still Matter
Trump’s September 26 statement marked the political sign-off, but it did not spell out the final miles-per-gallon targets, compliance schedule or credit provisions. That distinction matters because the formal rulemaking had already moved well beyond the proposal stage. The White House Office of Information and Regulatory Affairs finished reviewing NHTSA’s final rule on August 12 and classified the action as “Consistent with Change.” The federal regulatory agenda listed September 2026 as the expected final-rule month, yet the OIRA record still showed no publication date when Trump announced his approval.
The best public numerical baseline therefore remains NHTSA’s December 2025 proposal. That plan projected an industrywide passenger-car and light-truck average of about 34.5 mpg in model year 2031. It also proposed eliminating inter-manufacturer credit trading and changing the classification of certain vehicles beginning in model year 2028. Until the signed final text is published, those provisions are a guide to the administration’s direction rather than a substitute for the final legal requirements. For automakers planning vehicles years in advance, even seemingly small changes in compliance rules can affect engineering choices, pricing and the mix of vehicles offered to consumers.
The U.S. Benchmark Is Moving Far Below the 2024 Trajectory
The scale of the proposed U.S. reset becomes clearer when it is placed beside the rule NHTSA finalized in June 2024. That earlier framework called for passenger-car standards to rise by about 2% a year for model years 2027 through 2031 and for light-truck standards to rise by about 2% annually from model years 2029 through 2031. NHTSA estimated that the combined industry fleet would reach roughly 50.4 mpg in model year 2031. The figure was never a requirement that every vehicle sitting on a dealer lot achieve 50.4 mpg; it represented an estimated fleetwide outcome under the agency’s footprint-based compliance system.
The Trump administration’s last published proposal was substantially less stringent. It proposed increases of 0.5% annually through model year 2026, followed by a model-year 2027 bridge and increases of 0.25% annually through 2031. NHTSA projected that framework would correspond to roughly 34.5 mpg fleetwide in 2031—about 16 mpg below the 2024 projection. In practical terms, less stringent requirements can give manufacturers more flexibility to meet demand for larger gasoline-powered vehicles without depending as heavily on efficiency improvements, hybrids or EVs to satisfy CAFE obligations. The precise size of that flexibility will depend on what survives into the final rule.
Lower Upfront Costs Come With a Fuel-Use Trade-Off
The administration has presented the weaker standards primarily as an affordability measure. When the proposal was unveiled in December 2025, the Transportation Department said its approach could generate more than $109 billion in savings over five years and lower the average price of a new vehicle by roughly $1,000. NHTSA’s analysis, reported by Reuters, put the modeled average reduction in upfront vehicle costs at about $930. Those figures depend on assumptions about technology costs and how manufacturer savings are ultimately passed through to buyers; they do not mean every vehicle would automatically receive a four-figure price cut.
The same analysis identified costs that would arrive later rather than at the dealership. Reuters reported that NHTSA estimated the proposal could increase U.S. fuel consumption by about 100 billion gallons through 2050 and add roughly $185 billion to fuel expenditures compared with the Biden-era standards. The agency’s analysis also projected carbon-dioxide emissions would be about 5% higher over that period. The trade-off is relatively straightforward: lowering the amount of efficiency technology required in new vehicles can reduce upfront compliance costs while increasing fuel use later. How that balance looks for an individual household depends heavily on annual mileage, fuel prices, vehicle type and how long a vehicle stays on the road.
Canada Is Repealing Its EV Mandate — but Not Its Emissions Push
Canada is changing course too, but in a different direction. The federal Electric Vehicle Availability Standard currently includes explicit zero-emission requirements of 20% for model year 2026, 60% by 2030 and 100% from 2035 onward. Ottawa’s August 2026 regulatory proposal would repeal those requirements and their associated compliance system. That represents a major change from the framework adopted in 2023, which was built around steadily escalating annual ZEV targets and credits rather than relying exclusively on fleetwide greenhouse-gas performance.
At the same time, the federal government has not abandoned tighter vehicle-emissions policy. Its February auto strategy committed to stronger greenhouse-gas standards for model years 2027–32. Ottawa says those standards will be technology-neutral in the early years, allowing manufacturers to use a wider array of technologies while putting Canada on a path toward a goal of 75% EV sales by 2035 and 90% by 2040. Importantly, the August repeal proposal does not yet contain the complete numerical design of those stronger replacement standards. Canada is therefore moving away from a direct EV sales requirement while preparing a separate, tougher Canadian fleet-emissions framework.
A Longstanding Regulatory Partnership Is Splitting
For years, Canada’s light-duty vehicle greenhouse-gas rules were built around close alignment with the United States. Canada’s regulations incorporated important parts of U.S. Environmental Protection Agency standards and test procedures, allowing manufacturers to plan largely common vehicles for both markets. The Canadian regulations adopted in 2010 explicitly described alignment with federal U.S. requirements as part of their purpose. That approach made commercial sense for an industry in which Canadian factories, U.S. factories and parts suppliers often operate as pieces of one continental production system rather than completely separate national industries.
That structure became more difficult to maintain after the U.S. EPA finalized the rescission of its motor-vehicle greenhouse-gas standards in February 2026. Canada’s proposed amendments respond partly by changing references so the Canadian system can continue despite the American repeal, while Ottawa develops a more distinctly Canadian path. One important distinction can easily get lost: EPA greenhouse-gas regulations and NHTSA fuel-economy standards are separate U.S. programs. EPA itself says its February action did not rescind CAFE standards, which are administered by NHTSA under different statutory authority. Trump’s newly approved fuel-economy action therefore represents another, separate change to the U.S. regulatory system.
One Integrated Auto Market Now Faces Diverging Rules
The regulatory split matters because the Canadian and U.S. auto industries are not cleanly separable. Canada’s federal auto strategy says the sector supports more than 500,000 workers, contributes more than $16 billion annually to Canadian GDP and produced more than 1.2 million passenger vehicles in 2025. Industry data show how dependent the production system remains on cross-border trade. The Canadian Vehicle Manufacturers’ Association says motor vehicles were Canada’s second-largest export by value in 2024, worth $46.5 billion, and 92% of those exports went to the United States.
The physical supply chain is even more intertwined than the headline trade totals suggest. The CVMA says parts and components can cross Canadian, U.S. and Mexican borders as many as eight times before being installed in a finished vehicle. Divergent fuel-economy and emissions rules therefore affect more than regulatory paperwork in two isolated markets. They can influence which engines, batteries, hybrid systems and vehicle configurations manufacturers prioritize across shared platforms. Automakers can still develop different compliance mixes for each country, but greater regulatory separation places a premium on flexible powertrains and product planning—especially for manufacturers selling similar pickups, SUVs and crossovers on both sides of the border.
EV and Hybrid Sales Show Why the Policy Debate Is Shifting
Recent market data help explain why policymakers and manufacturers are paying closer attention to flexibility. Canada’s 2026 regulatory analysis reported that the ZEV share dropped from roughly 14% in 2024 to about 9% in 2025. During the first four months of 2026, the average was around 10%, with March reaching roughly 12%. Those numbers remained well short of the 20% requirement contained in the existing federal EV Availability Standard for model year 2026, illustrating the gap that had developed between the regulated trajectory and recent market demand.
The United States is also experiencing a mixed powertrain transition rather than a simple switch from gasoline to fully electric vehicles. The Alliance for Automotive Innovation reported that EVs accounted for 7.9% of new U.S. light-duty vehicle sales in the second quarter of 2026, with 161 electric models available. Hybrid market share climbed to 22.2%, up 4.9 percentage points year over year, while gasoline and diesel vehicles still represented 69.9% of sales. That pattern helps explain why technology-neutral approaches are receiving attention: hybrids can deliver efficiency gains without requiring every buyer to move immediately to a fully electric vehicle, while EV demand continues to develop unevenly across regions and vehicle segments.
The MPG Headline Needs Context
The large gap between 34.5 mpg and 50.4 mpg is easy to read as a direct comparison with the fuel-economy label attached to a new vehicle, but CAFE does not work that way. NHTSA’s 2024 final rule explained that real-world fuel economy is generally 20% to 30% below the estimated required CAFE level. The agency also stressed that the actual standards consist of footprint-based target curves for passenger cars and light trucks. In other words, a manufacturer’s compliance obligation varies according to the size and composition of the vehicles it sells rather than being one identical mileage requirement applied to every model.
That nuance applies to both the old and proposed new numbers. A projected industrywide CAFE level of 50.4 mpg never meant every 2031 pickup, SUV and sedan would need to deliver 50.4 mpg during ordinary driving. Likewise, the Trump administration proposal’s roughly 34.5-mpg projection should not be interpreted as the future window-sticker rating for every American vehicle. A company heavily weighted toward larger trucks faces a different footprint-based calculation than a manufacturer selling mostly smaller vehicles. That is why a dramatic change in the fleetwide CAFE projection can be genuinely important for industry strategy without translating one-for-one into the fuel-economy number an individual driver sees on a dashboard or dealership label.
The 2027–32 Story Is Still Being Written
The U.S. side is near the end of its rulemaking process, but Trump’s September 26 announcement arrived before the complete final text and numerical details were publicly available. OIRA completed its review on August 12, and the federal regulatory agenda listed September for publication of the final rule. The eventual published text will establish exactly how closely the standards track NHTSA’s 34.5-mpg proposal, how credit trading and vehicle classification are handled, and when individual provisions take effect. Those details can matter as much to manufacturers as the headline mpg figure because product and powertrain decisions are typically made years before a model reaches a dealership.
Canada is at an earlier stage. The proposed repeal of the EV sales requirements was published on August 15, and the federal consultation remains open through October 29, 2026. Separately, Ottawa says consultations will shape the strengthened light-duty GHG standards promised for model years 2027–32. The broad direction on both sides of the border is therefore visible, but important regulatory details remain unsettled. Washington is moving toward substantially less stringent federal fuel-economy requirements, while Canada is replacing a prescriptive EV mandate with plans for stronger Canada-specific emissions standards. For an auto industry accustomed to deep regulatory and manufacturing integration, that divergence may become one of the most consequential planning issues of the next several model years.