




















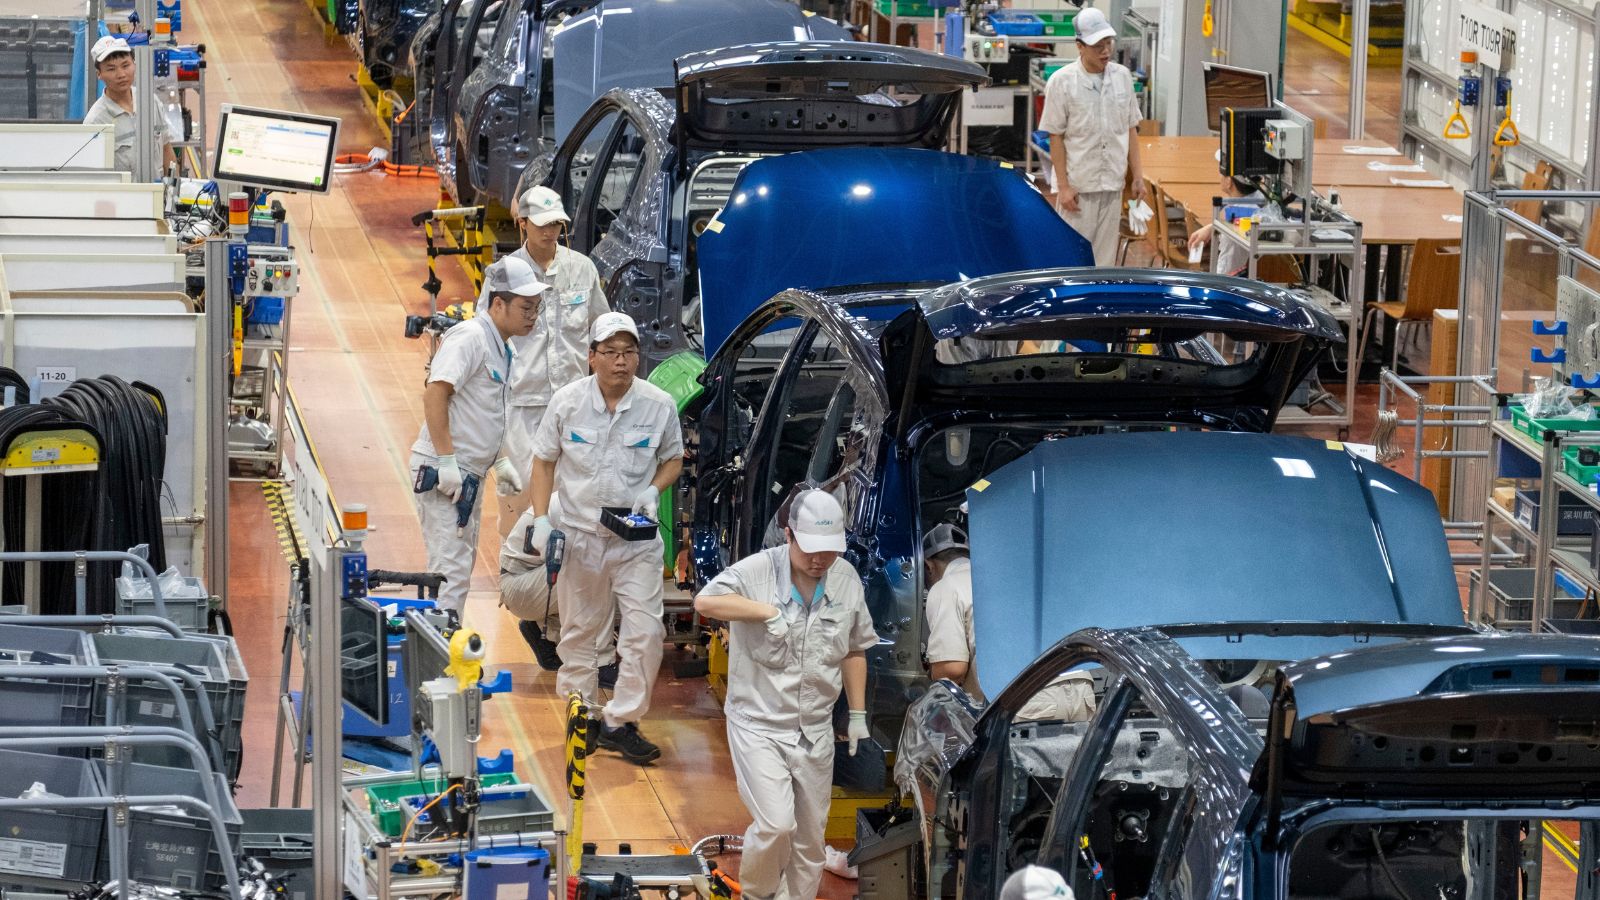
Canada’s automotive manufacturing industry suffered another setback in August 2026, with vehicle assembly sales falling 4% and auto parts manufacturers recording a 4.2% decline. Statistics Canada released the figures on October 15, identifying weaker-than-usual seasonal activity and an extended summer shutdown at a major assembly plant as factors behind the disappointing performance.
The decline occurred even as Canada’s overall manufacturing sales increased 1.5% to nearly $79.9 billion, revealing a widening divide between automotive production and other industrial sectors.
For workers, suppliers and communities that depend on vehicle manufacturing, the numbers highlight an uncomfortable reality. A slowdown at one major factory can create challenges throughout a closely connected supply chain, particularly as Canadian automakers navigate changing production schedules, U.S. tariffs and an uncertain North American trade environment.
Canadian Vehicle Assembly Sales Fall 4% in August
Canadian motor vehicle manufacturers recorded $4.47 billion in sales during August 2026, down from approximately $4.65 billion in July. The 4% decline represents roughly $188 million in reduced monthly factory sales. According to Statistics Canada’s latest Monthly Survey of Manufacturing, the contraction contributed to a broader 2.6% reduction in transportation equipment manufacturing, where sales fell to approximately $12 billion. That category includes not only passenger vehicles but also aerospace equipment, automotive components, commercial transportation products and other manufacturing activities.
The monthly decline should be considered alongside the longer-term numbers. Despite August’s disappointing performance, motor vehicle manufacturing sales remained 10.5% higher than in August 2025, when they stood at approximately $4.04 billion. That comparison demonstrates how factory activity can fluctuate significantly between reporting periods without necessarily signalling a continuous year-long contraction. Nevertheless, falling production-related sales create immediate operational challenges. Assembly plants depend on carefully coordinated schedules, suppliers depend on consistent orders, and workers depend on predictable shifts. Even a temporary disruption can affect how efficiently the entire system operates.
Extended Summer Shutdown Disrupts a Major Canadian Assembly Plant
Statistics Canada identified an extended summer shutdown at a major automotive assembly plant as one of the explanations for August’s decline. The agency also pointed to weaker-than-usual seasonal sales activity. Automotive factories typically schedule maintenance, equipment adjustments and model-change preparations around summer production breaks. These interruptions allow manufacturers to perform work that would be difficult while assembly lines are running at normal capacity. However, when a shutdown extends beyond its usual schedule, the resulting loss of production time can become visible in national manufacturing statistics.
The latest report did not identify the affected assembly plant by name, making it important not to attribute the disruption to a particular automaker without additional confirmation. An extended shutdown also does not automatically mean that a factory is closing permanently or that workers are losing their jobs. The economic consequences depend on the duration, the reason for the interruption and whether production eventually resumes at its previous pace. For nearby suppliers and businesses, however, the distinction may offer limited immediate comfort. Fewer vehicles coming off an assembly line can mean fewer components ordered, fewer transportation movements and additional uncertainty about upcoming production schedules.
Auto Parts Manufacturers Report a 4.2% Decline
The slowdown extended beyond companies assembling finished vehicles. Canadian motor vehicle parts manufacturers reported August sales of approximately $3.06 billion, compared with $3.19 billion in July. The 4.2% decrease represents about $134 million in lost monthly sales. Parts manufacturing remains a crucial part of Canada’s automotive industry, supplying everything from structural components and braking systems to electronic equipment and powertrain assemblies. The sector is also closely connected to American manufacturing operations, making its performance sensitive to production schedules on both sides of the border.
The relationship between assembly plants and suppliers helps explain why disruptions can spread quickly. Automotive production frequently relies on components arriving shortly before they are needed, reducing the cost of storing large inventories. When an assembly plant slows down, orders to nearby suppliers may also change. Some manufacturers must adjust operating hours or production schedules even when their own equipment remains functional. August’s numbers do contain one encouraging comparison: Canadian parts manufacturing sales were still 7.2% higher than a year earlier. The immediate challenge is restoring consistent month-to-month activity rather than assuming that the latest setback represents a permanent decline.
Overall Canadian Manufacturing Sales Rise Despite Automotive Weakness
Canada’s manufacturing sector actually expanded during August, making the automotive decline especially notable. Statistics Canada reported that total factory sales increased 1.5% to approximately $79.9 billion, reversing a revised 0.3% decline in July. Sales increased in 12 of the country’s 21 manufacturing subsectors. Compared with August 2025, overall manufacturing sales were 14.2% higher. These results show that weakness in vehicle production did not prevent other Canadian industries from recording substantial increases. However, they also demonstrate why national manufacturing statistics can sometimes hide important differences between individual sectors.
A particularly revealing measure is manufacturing sales excluding motor vehicles, parts and accessories. That category increased 2.1% in August, outperforming the 1.5% gain for manufacturing as a whole. Another important distinction involves inflation. Although the dollar value of total manufacturing sales increased, sales measured in constant dollars were essentially unchanged. Statistics Canada also recorded a 1.3% increase in industrial producer prices during the month. In other words, stronger nominal factory sales did not translate into an equivalent increase in the volume of goods sold. For the automotive industry, where production schedules and factory utilization are important, that distinction adds useful context.
Strong Metal and Chemical Sales Offset Transportation Equipment Losses
Primary metal manufacturing delivered one of the strongest performances in Canada’s latest industrial figures. Sales climbed 14% in August to approximately $7.6 billion, reaching a record high. Statistics Canada reported that much of the increase came from non-ferrous metals other than aluminum, supported by stronger prices and production volumes. In constant dollars, primary metal sales rose 9.1%, confirming that the improvement was not exclusively a result of higher prices. Growing industrial applications for copper, silver and other metals, including electrification and renewable-energy technologies, have contributed to stronger demand.
Chemical manufacturers also reported an improvement, with sales increasing 4.4% to approximately $6.2 billion. Higher basic chemical sales were an important contributor, although inflation-adjusted chemical sales increased only 0.4%. These gains helped offset the 2.6% contraction in transportation equipment manufacturing. For Canadian policymakers, the contrasting results present a complicated economic picture. Industries associated with metals and industrial inputs are benefiting from stronger demand, while vehicle manufacturers are struggling with production interruptions. The differences show why an improving national manufacturing total does not necessarily mean that every industrial community is experiencing an economic recovery.
Ontario Manufacturing Holds Steady While Quebec Posts Strong Growth
Ontario occupies a particularly important position in Canada’s automotive industry, hosting major assembly operations and an extensive network of component manufacturers. However, its overall factory sales were effectively unchanged in August, declining by less than 0.1% to approximately $32.94 billion. That result contrasts with stronger performances elsewhere in the country. Quebec recorded a 4% increase to approximately $21 billion, supported primarily by higher primary metal sales. Newfoundland and Labrador reported an even larger percentage gain of 58.5%, with manufacturing sales reaching $692 million. These figures illustrate how provincial economic performance depends heavily on the industries concentrated within each region.
Ontario’s stable headline figure should not be interpreted as evidence that its automotive businesses escaped August’s problems. The province’s factory activity spans many industries, meaning stronger results in one sector can offset weakness in another. The Financial Accountability Office of Ontario had previously reported a 7.7% increase in provincial manufacturing sales during the second quarter of 2026, following a weaker first quarter. That rebound was helped by transportation equipment, petroleum products and machinery. August’s national automotive decline therefore adds another complication to a recovery that has already been uneven. For communities centred around assembly plants, the return of dependable vehicle production remains more important than the performance of unrelated industries.
Automotive Wholesale Sales Also Decline as Inventories Shrink
The weakness in automotive manufacturing coincided with another disappointing result further along the vehicle distribution chain. Statistics Canada’s separate wholesale trade report, also released October 15, showed that sales by motor vehicle and parts wholesalers declined 3.8% in August to $15.1 billion. The decrease followed six consecutive months of growth. Within that category, motor vehicle wholesale sales fell 4.6% to $12.1 billion. Ontario, the country’s largest automotive manufacturing centre, recorded a 3.7% decline in automotive wholesale sales to approximately $10.5 billion. Together, these figures suggest that August was a challenging month for businesses involved in both producing and distributing vehicles.
Inventories provide another indication of changing market conditions. Motor vehicle and parts wholesalers reported a 3.7% reduction in inventories, bringing their combined stock to approximately $17.9 billion. However, wholesale sales and factory sales measure different business activities and should not be added together or treated as evidence of the same transaction. The data also cannot establish that the assembly plant’s extended shutdown directly caused weaker wholesale demand. What they demonstrate is that two important stages of Canada’s automotive industry experienced declines during the same month.
Canada’s Auto Industry Remains Deeply Exposed to U.S. Trade Policies
Canada’s automotive sector is unusually dependent on access to the American market. According to the federal government, more than 90% of Canadian-made vehicles and approximately 60% of Canadian-made automotive parts are exported to the United States. The industry supported approximately 125,000 direct jobs and produced more than 1.2 million passenger vehicles in 2025. Those figures explain why changes in American tariffs or vehicle-production strategies can have consequences far beyond the border. Canadian assembly plants are not isolated operations; they are part of a highly integrated continental manufacturing network.
Since April 2025, Canadian-made vehicles have faced a 25% American tariff on their non-U.S. content, with the value of U.S. components in qualifying CUSMA-compliant vehicles exempted. The distinction is important because the duty does not apply uniformly to every dollar of a qualifying vehicle’s value. Ottawa’s automotive strategy, announced in February 2026, includes industrial investment support, measures for workers and efforts to strengthen domestic production. However, Statistics Canada’s August report did not identify tariffs as the cause of the specific extended summer shutdown. Trade policy remains a major structural pressure, rather than a verified explanation for that particular interruption.
Vehicle Exports Rise Even as Domestic Factory Sales Retreat
One of August’s more surprising developments appeared in Canada’s international trade figures. Global Affairs Canada’s monthly report showed that exports of motor vehicles and parts increased 4% from July, despite the simultaneous decline in Canadian automotive manufacturing sales. Imports of vehicles and parts moved sharply in the opposite direction, falling 8.8% after reaching a record high in July. At first glance, stronger exports might appear inconsistent with weaker factory performance. In reality, the figures measure different transactions and can move in opposite directions without indicating an error.
Manufacturing sales reflect goods sold by Canadian factories, while international merchandise trade captures goods crossing the border under a separate statistical framework. Differences in shipment timing, inventories, imported components and product mix can affect the relationship between the two measures. Canada’s overall goods exports also increased 2.5% in August, supported by several non-automotive categories. The trade figures therefore provide a more complicated picture than the factory data alone. Canadian automotive businesses were still shipping substantial products to international customers, even as domestic assembly and parts manufacturing reported weaker monthly sales. Determining whether that divergence persists will require additional months of data.
Factory Shutdowns Create Uncertainty for Workers and Auto Towns
For automotive workers, the consequences of disrupted production can extend beyond a disappointing monthly sales figure. A factory operating below its normal schedule may reduce overtime, alter shifts or delay orders to suppliers. Yet employment statistics reveal a more complicated picture. Canada’s overall manufacturing workforce increased by approximately 22,000 people in August, before declining by 13,000 in September, according to Statistics Canada. These figures cover the entire manufacturing sector, not just automotive jobs. They also demonstrate why a drop in factory sales cannot automatically be translated into an equivalent loss of employment.
A separate example of the uncertainty facing automotive communities involves Stellantis’s Brampton, Ontario, assembly plant. The facility, which previously employed approximately 2,200 workers, closed for retooling in 2024 before that work was paused in 2025. In August 2026, Unifor reported that Stellantis was considering discussions about a possible sale of the property. This long-running situation is distinct from the unnamed extended summer shutdown identified in Statistics Canada’s latest manufacturing report. Nevertheless, it illustrates the human stakes behind production decisions. For affected households and nearby businesses, uncertainty over a factory’s future can be just as disruptive as an announced permanent closure.
Investment Plans Offer Hope, but the Next Production Figures Will Be Crucial
Despite the industry’s difficulties, manufacturers continue to consider substantial investments in Canadian production. In August, a tentative agreement between General Motors and Unifor outlined approximately $1.1 billion in investment commitments for Canadian automotive operations. The proposed spending included $144 million to support production of a next-generation heavy-duty GMC Sierra pickup in Oshawa and $215 million for a new transmission program in St. Catharines, scheduled to begin in late 2029. These plans offer potential support for Canada’s manufacturing base, although investment announcements should not be mistaken for completed projects or immediate increases in production.
The next round of manufacturing statistics will help determine whether August’s automotive weakness was largely temporary. Across Canadian manufacturing as a whole, inventories increased 0.2% to $127.7 billion in August, while unfilled orders remained essentially unchanged at $134.2 billion. The sector’s capacity utilization rate also increased from 80.7% in July to 81.9% in August, although that improvement does not specifically describe automotive factories. Statistics Canada is scheduled to publish an advance estimate for September manufacturing sales on October 23, followed by detailed results on November 13. For Canada’s automotive industry, the central questions remain whether interrupted assembly operations return to normal, whether parts suppliers regain consistent orders and whether manufacturers can maintain long-term production commitments. August’s decline is a warning sign, but subsequent results will determine whether it marks a temporary disruption or a deeper industry slowdown.