





















America’s electric-vehicle market is producing two seemingly contradictory signals. New EV sales have fallen dramatically from last year’s incentive-fueled highs, with August volume nearly 47% below August 2025. Yet companies responsible for keeping those vehicles moving are still installing chargers at close to the pace established during 2025’s record infrastructure expansion.
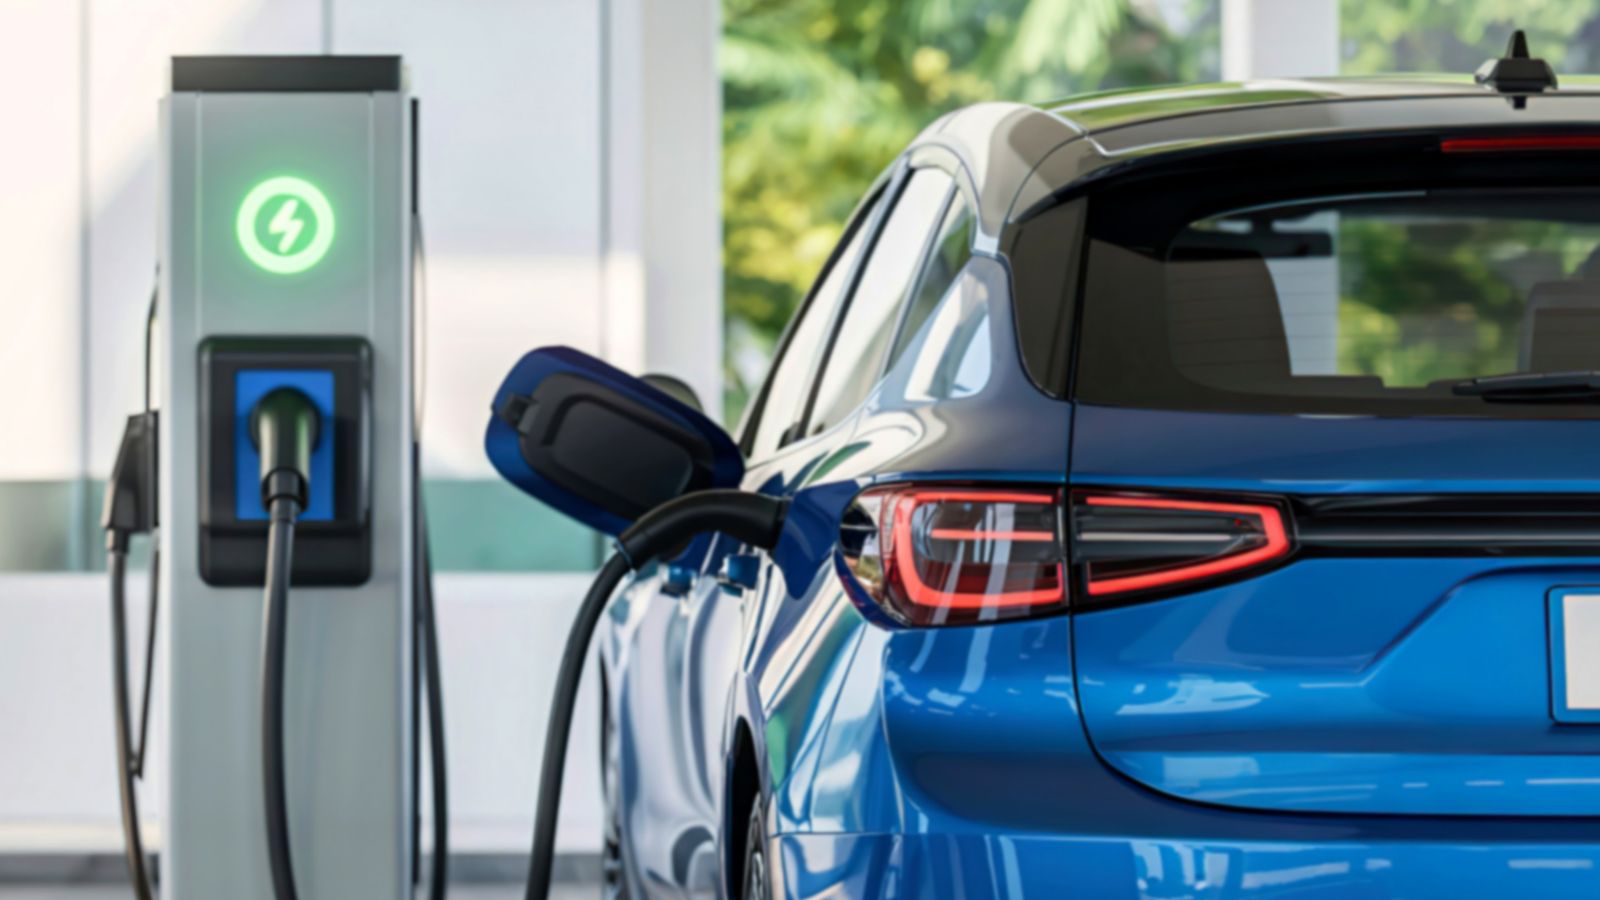
The split says something important about where the U.S. EV transition stands. New-car demand weakened sharply after federal purchase incentives disappeared, but millions of electric vehicles already on American roads still need dependable places to charge. Operators are consequently building larger stations, adding faster equipment and trying to improve reliability even while automakers reassess their EV strategies. The result is a market in which vehicle sales have cooled much faster than the infrastructure supporting them.
The Headline Drop Is Nearly 50%—But the Timeframe Matters
Americans purchased an estimated 78,895 new electric vehicles in August 2026, according to Cox Automotive. That represented a 46.9% decline from August 2025, making the description of sales falling “by half” a reasonable shorthand for that year-over-year monthly comparison. The same data, however, showed sales increasing 2.5% from July. EVs accounted for 5.7% of all new vehicles sold during August, essentially unchanged from the previous month.
That distinction prevents a dramatic statistic from becoming a misleading one. August 2025 was an exceptionally strong comparison month as consumers hurried to secure federal incentives before they disappeared. The 2026 market is clearly much weaker than that peak, but it is not contracting by half every month. Tesla still accounted for 40,816 August sales, or 51.7% of the new-EV market, while Toyota, Rivian, Hyundai and Cadillac followed. Several manufacturers increased EV sales from July, suggesting that demand has found a lower level rather than simply disappearing.
The Federal Tax Credit Created an Unusual Comparison
The policy change behind much of the sales swing is unusually easy to identify. The Internal Revenue Service says the New Clean Vehicle Credit, Previously-Owned Clean Vehicle Credit and Qualified Commercial Clean Vehicle Credit are unavailable for vehicles acquired after September 30, 2025. Before that deadline, an eligible new vehicle could potentially bring a federal incentive worth as much as $7,500, giving shoppers a significant reason to purchase sooner rather than later.
That deadline effectively shifted some future demand into the summer and early fall of 2025. The National Automobile Dealers Association has specifically cautioned that last year’s sales volumes were inflated in the months leading up to the expiration of the credits. A buyer who might otherwise have waited until winter had thousands of dollars of motivation to sign a deal before October arrived. When 2026 sales are compared with those unusually busy months, the percentage decline therefore looks especially severe. The underlying weakness is real, but the comparison point magnifies it.
The Full-Year Picture Is Weaker, but Not Down by Half
Looking beyond one month produces a more measured picture. Through September 2026, U.S. battery-electric vehicle sales were down 29.2% from the comparable period a year earlier, according to NADA. Battery electrics represented 6.2% of new light-vehicle sales through September, 2.3 percentage points below their year-earlier share. That remains a substantial retreat, but it is clearly different from saying the entire American EV market has been cut in half.
Consumers have not abandoned electrification altogether. Conventional hybrid sales increased 22.4% through September and captured 15.6% of the new-vehicle market, up 3.1 percentage points. That divergence helps explain what is happening in showrooms. Many buyers interested in reducing fuel consumption are choosing vehicles that do not require regular plugging in. Hybrids offer an electrified powertrain while preserving the familiar refueling experience of a gasoline vehicle. For automakers, the result is an increasingly complicated market in which electrification continues growing even while pure battery-electric sales struggle.
Charging Construction Is Moving in the Opposite Direction
The charging business has not followed new-EV sales downward at the same speed. Charging companies are on track to install roughly as many public EV plugs in the United States during 2026 as they did during 2025, which was a record year for additions. That continuing investment is striking precisely because it is happening while new-EV demand remains significantly below last year’s peak.
The foundation was already substantial. The International Energy Agency reported that the United States added a record number of public charging points in 2025, with additions running 20% above the previous year. The number of fast and ultra-fast charging points grew about 30% to nearly 70,000, while slower public charging points exceeded 160,000. Infrastructure operators are planning for a fleet that exists for years rather than one month’s showroom traffic. A charger installed today can serve vehicles bought in 2022, used cars changing owners in 2026 and models that have not yet reached dealerships.
Fast-Charging Operators Are Still Adding Thousands of Ports
The more specialized DC fast-charging market provides another view of that momentum. Paren reported that approximately 3,500 new public fast-charging ports came online during the first quarter of 2026. Deployment accelerated in the second quarter, when operators opened 4,382 ports across 806 new stations. Although that Q2 total was below the 4,865 ports added during the same quarter of 2025, it remained an unusually large expansion by historical standards.
More important, new capacity has not caused utilization to collapse. Paren measured national fast-charger utilization at about 15.8% during the second quarter, compared with roughly 15.6% in the first. Monthly charging sessions increased from approximately 14.1 million in April to 16.1 million in June. In other words, operators were adding plugs while motorists were also using the network more frequently. That helps explain why charging companies can continue expanding during a new-EV sales downturn: demand comes from the accumulating population of vehicles already on the road, not just cars purchased during the latest month.
New Charging Sites Are Being Built Bigger and Faster
The charging buildout is also changing in character. The industry increasingly emphasizes the number and capability of plugs at each location rather than simply putting another dot on a map. Paren found that more than 18,000 new U.S. DC fast-charging ports were installed during record-setting 2025. As the year progressed, higher-power equipment became increasingly common: chargers rated at 250 kilowatts or above represented 27% of newly deployed ports in the first quarter but 51% by the fourth.
That trend has continued into 2026, with operators emphasizing higher-capacity locations capable of handling more vehicles. EVgo provided an extreme example in September when it previewed a next-generation charging system capable of delivering as much as 750 kW. The final hardware is expected to be introduced in 2027, and real charging speeds will remain limited by what individual vehicles can accept. Still, the announcement illustrates where the infrastructure business is headed: more plugs, greater power and stations designed around higher throughput rather than minimal coverage.
Used EV Buyers Are Becoming More Important to the Network
New-car statistics also miss another growing source of charging demand: the used market. Cox Automotive estimated that 44,350 used EVs were sold in August, an increase of 25.9% from July and 14.7% from a year earlier. Growing numbers of lease returns and trade-ins are putting several-year-old electric vehicles into a price range accessible to buyers who may never have considered purchasing one new.
That matters to charging operators because a used EV places essentially the same infrastructure demands on the network as a new one. Its next owner still needs charging near apartments, shopping areas and highways. The growth is particularly notable because the federal Previously-Owned Clean Vehicle Credit also ended for vehicles acquired after September 30, 2025. In other words, used EV activity is expanding without the federal consumer credit that once helped subsidize eligible purchases. For a charging company deciding whether a new station will attract customers over the next decade, the expanding secondhand fleet may matter as much as disappointing new-car sales today.
Charging Companies Are Growing Even While Profits Remain Difficult
Building a charging network does not automatically mean earning a profit. EVgo reported $61 million in charging-network revenue during the second quarter of 2026, up 19% from a year earlier. Network energy throughput rose 13%, and the company ended June with 5,380 operating stalls across its public, autonomous-vehicle and eXtend operations, 24% more than a year earlier. Yet EVgo still recorded a quarterly net loss of approximately $46.3 million.
ChargePoint illustrates a similar tension from a different business model. Its fiscal second-quarter 2027 revenue reached $116.1 million, 18% above the prior-year period, while networked charging-system revenue increased 25%. The company nevertheless reported a GAAP net loss of $35.6 million, although its adjusted EBITDA loss narrowed sharply to $4.8 million from $22.1 million a year earlier. These results explain why the infrastructure boom should not be confused with an easy business. Networks must keep expanding and improving while simultaneously trying to turn growing usage into sustainable economics.
Private Investment Has Been Doing Much of the Heavy Lifting
Federal programs remain part of the charging story, but private operators have accounted for much of the recent expansion. Paren estimated that only around 3% of the DC fast-charging ports installed during 2025 were funded through the National Electric Vehicle Infrastructure program. Tesla and a widening field of private and automaker-backed networks supplied most of the rest, helping the charging buildout continue despite uncertainty surrounding federal policy.
Government-supported deployment is progressing nonetheless. The IEA reported that about 550 NEVI-funded fast-charging points were operational across 19 states by April 2026, with roughly another 1,000 points already awarded funding. A Congressional Research Service report subsequently estimated that 183 NEVI-funded charging stations had opened across 20 states. The broader NEVI and Charging and Fueling Infrastructure programs originated from $7.5 billion allocated under the 2021 infrastructure law. Federal incentives have therefore helped fill corridor gaps, but the latest expansion cannot accurately be described as a purely government-built charging network.
Better Charging Could Matter More During a Sales Slowdown
Infrastructure improvements are increasingly visible to the people who already own electric vehicles. J.D. Power’s 2026 ownership study found that 96% of new battery-electric vehicle owners surveyed would consider buying or leasing another BEV. Satisfaction with public charging availability improved substantially, rising 101 points year over year among premium-BEV owners and 115 points among mass-market owners on the study’s 1,000-point scale.
Broader consumer research also points to changing perceptions. The 2026 HERE-SBD EV Index found that 53% of surveyed Americans said they were more open to considering an EV than they had been a year earlier. Positive perceptions of public charging availability increased from 28% to 47%. Those findings do not guarantee that EV sales will rebound quickly; affordability, incentives, model choice and household charging access still matter. They do suggest that continuing to build the network during a weak sales year can remove one of the obstacles that has long made potential buyers hesitant.
The Two Trends Are Less Contradictory Than They First Appear
A nearly 50% year-over-year monthly sales decline alongside record-like charging expansion can look like an industry building infrastructure for customers who are no longer coming. The underlying data tells a more complicated story. August’s 46.9% decline was measured against an extraordinary incentive-driven month in 2025, while year-to-date battery-electric sales were down a smaller 29.2%. Used-EV sales, meanwhile, were growing, and millions of existing vehicles continued consuming more public charging sessions.
Charging infrastructure is also a long-lived investment. Stations opened in 2026 are intended to operate through multiple generations of vehicles and market cycles, not merely serve this year’s showroom volume. That makes the current divergence understandable. Automakers and consumers can adjust purchasing decisions rapidly when incentives disappear. Infrastructure, by contrast, has to anticipate where vehicles will be years from now. The crucial question is no longer simply whether America is installing enough chargers. It is whether the networks being built today can become reliable, convenient and financially sustainable before EV sales accelerate again.