

















A new vehicle can feel like a clean start: fresh warranty, newer safety systems, lower kilometres, and fewer repair worries. Yet insurance decisions made in the first few days after purchase can quietly shape costs and protection for years. Many Canadian drivers focus on the monthly payment, delivery date, and financing paperwork, only to treat insurance as a last-minute formality.
There are 16 common car insurance mistakes Canadians make after buying a new vehicle, ranging from missing depreciation protection to underestimating theft risk, skipping discounts, or forgetting to update how the vehicle is used. Each one may seem small at the dealership counter or during an online quote, but the impact can become expensive when a claim, renewal, loan balance, or policy review arrives.
Waiting Too Long To Notify The Insurer
One of the easiest mistakes is assuming insurance can be sorted out after the vehicle is already in the driveway. In most provinces, a new vehicle must be insured before it is driven on public roads, and a dealer or lender may require proof before releasing the keys. A buyer who relies on an old policy without confirming the new vehicle details risks misunderstanding what is actually covered.
The problem becomes sharper when the new vehicle is worth much more than the old one. A driver trading a ten-year-old sedan for a new SUV may have very different collision, comprehensive, theft, and liability needs. Even when a policy has a short automatic replacement window, the details vary by insurer and province. A quick call before pickup can prevent a stressful surprise later.
Assuming The Old Premium Will Stay Similar
Many buyers expect their insurance bill to move only slightly because their driving record has not changed. The vehicle itself, however, is a major rating factor. A new model may cost more to repair, have expensive sensors in the bumper, use specialized headlights, or sit in a higher theft-risk category. Even a trim upgrade can alter the cost because technology and parts prices affect claim payouts.
This is why two similarly priced vehicles can produce very different quotes. A family replacing an older compact with a newer crossover may discover that safety features help in one category while repair complexity pushes the premium up in another. Canadian insurers use claims experience, vehicle value, theft patterns, repair costs, location, driving history, and coverage choices together. The purchase price is only one part of the story.
Skipping Depreciation Waiver Or Replacement Cost Coverage
A new vehicle can lose value quickly, yet a loan or lease balance may remain high. After a total loss or theft, a standard settlement may be based on the vehicle’s actual cash value rather than the original purchase price. That gap can be painful if the vehicle is written off early, especially when taxes, fees, interest, or negative equity were rolled into the deal.
Many Canadian drivers overlook depreciation waiver or replacement cost coverage because it sounds like a small add-on during an already expensive purchase. In Ontario, for example, OPCF 43 removes the insurer’s right to deduct depreciation from the vehicle’s value when settling certain claims. Similar protections exist under different names or rules elsewhere. The key mistake is not asking before the vehicle is too old to qualify.
Confusing Gap Insurance With Depreciation Protection
Gap insurance and depreciation waiver coverage are often discussed together, but they do not always solve the same problem. A depreciation waiver is generally tied to how the insurer values a new vehicle after a covered total loss. Gap protection, often sold through lenders or dealers, is usually designed to help cover the difference between the insurance settlement and the remaining loan or lease balance.
The distinction matters because a driver can still owe money after a write-off, especially with long-term financing, low down payments, or rolled-in debt from a previous vehicle. A buyer who assumes one product automatically replaces the other may end up with duplicate protection or, worse, a gap that neither product fills. The smarter move is to compare policy wording, exclusions, limits, time periods, and refund rules before signing.
Choosing The Lowest Liability Limit Without Thinking
Many provinces set legal minimums for third-party liability coverage, but minimum coverage is not always a comfortable financial cushion. In Ontario, the required minimum is $200,000, while Quebec requires at least $50,000 in civil liability through a private insurer. Those figures can look large until a serious crash involves injuries, multiple vehicles, property damage, lawsuits, or travel outside the province.
The mistake happens when buyers focus only on reducing the monthly premium after taking on a new car payment. Raising liability coverage often costs less than people expect compared with the potential consequences of being underinsured. A new vehicle does not reduce the chance of causing damage to someone else. In fact, a more powerful, larger, or unfamiliar vehicle can make careful coverage review even more important.
Dropping Collision Or Comprehensive Too Soon
Some drivers try to offset the cost of a new vehicle by trimming optional coverage. Collision and comprehensive may feel negotiable, especially to someone who has gone years without a claim. But if the vehicle is financed or leased, the lender or leasing company will usually require physical damage coverage to protect its interest in the vehicle.
Even for owners who paid cash, dropping these coverages too early can be risky. Collision generally responds to damage from crashes with another vehicle or object, while comprehensive usually handles non-collision losses such as theft, vandalism, fire, or certain weather events. A new vehicle parked outside during hail season, or a popular model targeted by thieves, may need broader protection than the owner’s previous car ever did.
Forgetting To Add The Lienholder Or Leasing Company
A financed or leased vehicle is not just a private purchase; another party has a financial interest in it. Buyers sometimes update the vehicle on the policy but forget to list the lender, lessor, or lienholder correctly. That can create problems with lease compliance, financing conditions, proof-of-insurance requests, or claim payments after a major loss.
This mistake often comes from rushing through dealership paperwork. The driver may leave with plates and insurance slips, assuming the dealer handled every detail. But the insurance policy still needs to reflect the correct ownership and finance information. Some leasing arrangements also require specific endorsements, liability limits, and deductibles. A quick review of the lease or finance contract beside the insurance documents can catch mismatches early.
Ignoring Theft Risk On Popular New Models
Auto theft remains a major insurance issue in Canada, even as recent national trends have shown improvement. High-demand SUVs, pickups, and newer vehicles with export value can attract organized theft groups. The financial impact extends beyond the owner whose vehicle disappears; theft claim costs place pressure on premiums across the market.
The mistake is treating theft as something that happens only in certain neighbourhoods or only to luxury cars. A new vehicle parked in a suburban driveway can still be an attractive target if the model is known for high resale demand or easier theft methods. Insurers may respond with higher premiums, tracking-device requirements, anti-theft discounts, or surcharges. Asking about theft exposure before renewal can prevent a nasty premium surprise.
Not Asking About Anti-Theft Discounts Or Requirements
Many new vehicles come with factory security features, but insurers may not automatically apply every available discount. Some companies may offer savings for approved immobilizers, alarms, tracking systems, steering-wheel locks, secure parking, or other theft-prevention measures. In higher-risk regions, an insurer may even require certain devices before offering full theft coverage on specific models.
The mistake is assuming the vehicle’s built-in technology is enough. A buyer may pay for an aftermarket tracker at the dealer but never tell the insurer, or may buy a high-theft model without realizing a specific anti-theft device could reduce cost or preserve coverage options. Keeping receipts, installation proof, and device details helps. It also creates a clearer paper trail if the vehicle is stolen.
Missing Winter Tire Discounts
Winter tires are a safety decision, but in some places they can also affect insurance costs. Ontario requires insurers to offer a discount for winter tires, though the exact percentage can vary by company. Elsewhere, discounts depend on the insurer, and Quebec has separate winter tire rules for seasonal use.
The mistake is installing winter tires and never reporting them. Some drivers assume the discount appears automatically because tires were bought through the dealership or installed at a shop. Insurers usually need confirmation, and some may ask for dates, tire specifications, receipts, or photos. For a household already paying more after buying a new vehicle, even a modest discount can help. It is also one of the simplest post-purchase updates to make.
Setting A Deductible That Only Looks Good On Paper
A higher deductible can lower the premium, which is tempting after a new vehicle purchase. The risk is choosing a deductible that would be difficult to pay after a claim. A $1,000 or $2,000 deductible may look manageable during a quote, but less so after a collision, windshield damage, theft recovery, or vandalism incident.
The deductible decision should match real cash flow, not just the cheapest premium. A driver with a tight budget after a down payment may be more exposed than expected. Lease and finance agreements may also limit how high a deductible can be. The best deductible is not always the lowest or highest; it is the amount that keeps the premium reasonable while still being payable during a stressful week.
Forgetting To Update Annual Kilometres And Commute Details
A new vehicle can change driving habits. Someone who once took transit may start commuting daily because the new car is more comfortable. Another driver may work from home more often and use the vehicle mainly on weekends. These changes matter because insurers often ask about annual kilometres, commute distance, and where the vehicle is usually driven.
The mistake is carrying over the old usage profile without checking it. If the vehicle is driven much more than declared, coverage issues or premium corrections can arise. If it is driven much less, the owner may be missing a low-mileage discount. A new vehicle purchase is a natural point to reset assumptions. The insurer’s questions should be treated as live details, not paperwork copied from the previous car.
Using The Vehicle For Delivery Or Rideshare Without Disclosure
A new vehicle may feel like an opportunity to earn extra income through rideshare, food delivery, courier work, or client visits. Standard personal auto insurance, however, is usually priced for personal use, commuting, and ordinary errands. Commercial or app-based driving can create a different risk profile because the vehicle spends more time on the road and may carry passengers or goods for payment.
The mistake is assuming platform coverage replaces the need to tell the personal insurer. Coverage can vary by province, company, app, and stage of the trip. A driver may be covered while actively carrying a passenger but exposed while waiting for a request, or vice versa, depending on the arrangement. Disclosure is essential before the first paid trip.
Not Comparing Quotes After The Vehicle Is Chosen
Many buyers compare vehicle prices intensely but accept the first insurance quote because delivery is happening quickly. That can be expensive. The Financial Consumer Agency of Canada advises consumers to shop around because premiums vary from one insurer to another. The same vehicle, driver, postal code, and coverage package can produce meaningfully different prices.
This mistake often comes from fatigue. After negotiating trade-in value, financing, warranties, and fees, insurance feels like one more chore. But a new vehicle can reset the entire policy, making it a good time to compare quotes, deductibles, optional coverages, bundle discounts, telematics programs, and payment options. A one-hour review can save money over several renewals, especially when the new premium is higher than expected.
Overlooking Bundle, Multi-Vehicle, Or Telematics Savings
New-vehicle buyers sometimes focus on coverage gaps but forget ordinary discounts. Insurers may offer savings for bundling home and auto coverage, insuring multiple vehicles, maintaining a clean record, using winter tires, installing anti-theft devices, choosing paperless billing, paying annually, or enrolling in usage-based insurance. Not every discount is available everywhere, and not every driver benefits from every program.
The mistake is assuming the quoted premium already includes everything. A household adding a second vehicle, replacing a commuter car, or moving a home policy to the same insurer may qualify for savings that were not discussed at the dealership. Telematics programs can also reward careful or low-mileage driving, though drivers should understand what data is collected and how it may affect pricing before enrolling.
Adding Accessories Or Modifications Without Updating Coverage
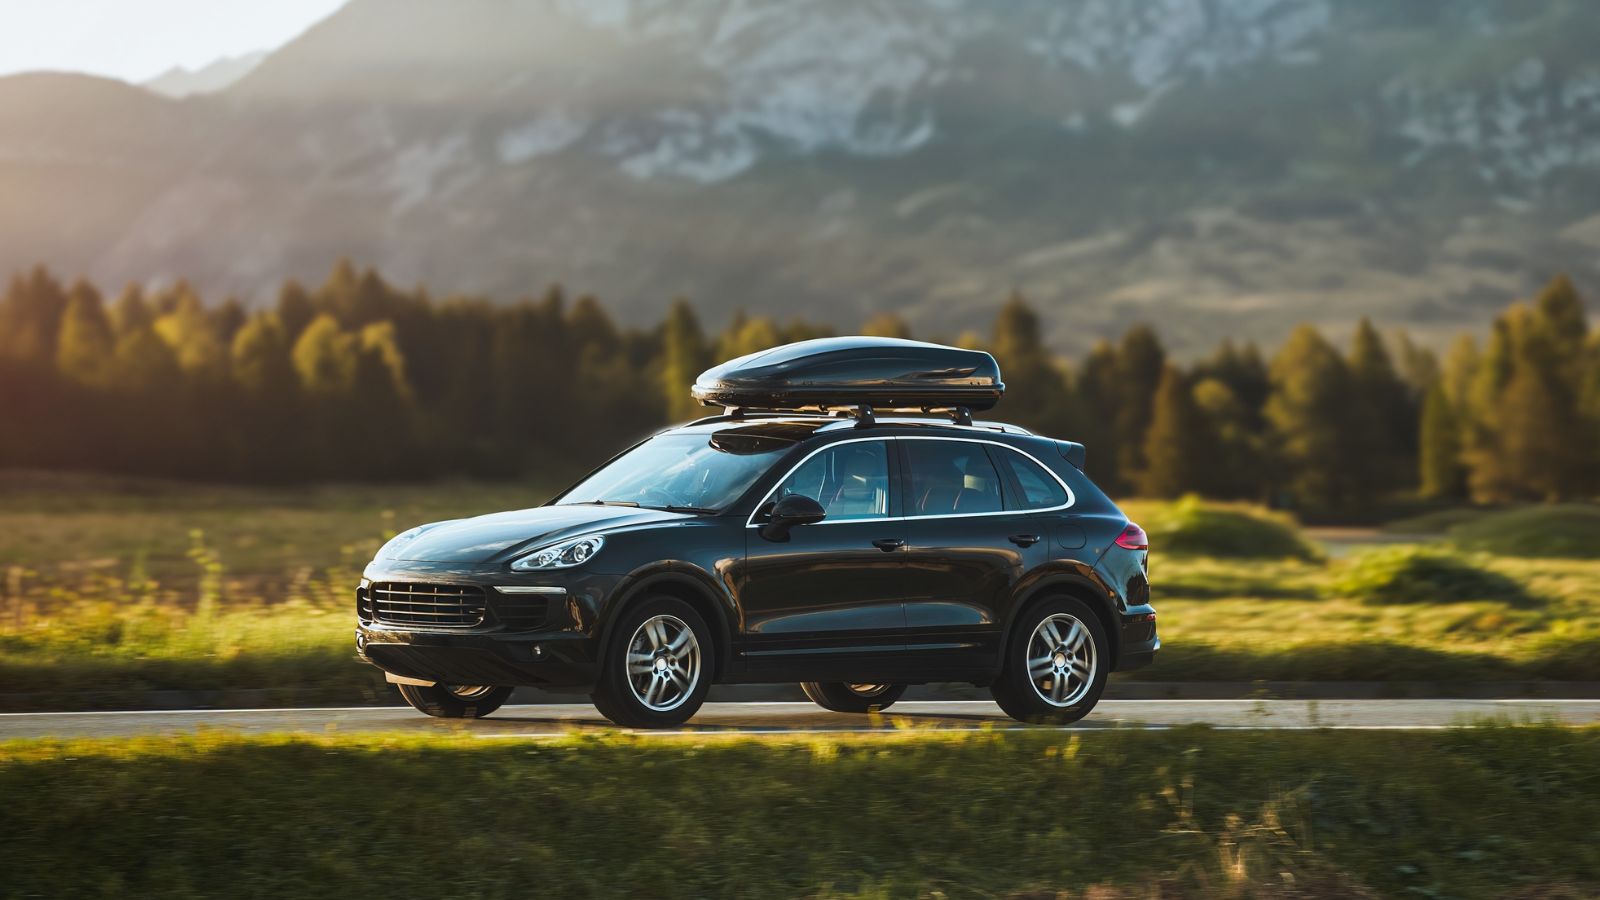
New vehicles often get accessories quickly: winter wheels, roof racks, running boards, upgraded audio systems, ceramic coatings, paint protection film, trailer hitches, or appearance packages. Some are installed at the dealer, while others are added after delivery. These upgrades can increase the vehicle’s value or alter its risk profile.
The mistake is assuming every add-on is automatically covered. Insurers may treat factory equipment, dealer-installed options, and aftermarket modifications differently. Performance modifications can affect insurability or pricing, while expensive accessories may need documentation. A driver who spends thousands after delivery should keep receipts and confirm coverage in writing. Otherwise, a theft or collision claim may not reimburse the full cost of what was added.
22 Things Canadians Do to Their Cars in Spring That Mechanics Hate
Spring brings relief to many Canadian drivers after months of snow, freezing temperatures, and icy roads that put serious strain on vehicles. As temperatures rise across the country, drivers begin washing cars, switching tires, and preparing vehicles for warmer weather and upcoming road trips. However, mechanics across Canada notice the same mistakes every spring when drivers attempt to recover from winter damage. Road salt, potholes, and harsh winter driving conditions often leave vehicles with hidden problems that drivers ignore. Some spring habits even create new mechanical issues that could have been avoided with proper maintenance. Here are 22 things Canadians do to their cars in spring that mechanics hate.