A new car can feel like a financial upgrade right up until the insurance quote arrives. The monthly payment may be predictable, yet the premium can move for reasons that are easy to overlook: the model’s claims history, theft exposure, repair technology, coverage choices, and even how the vehicle will be used.
In Canada, insurers price a combination of vehicle risk, driver history, location, coverage, and expected claims costs, so a higher bill does not always mean the new vehicle is inherently “riskier.” Sometimes the purchase simply triggers broader protection or coincides with a rate change already moving through the market. These 17 reasons explain the most common ways a new-vehicle purchase can push insurance costs upward—and why getting a quote before signing can prevent an unpleasant surprise.
Your New Model Has a Worse Claims Record
Two vehicles with similar prices can produce very different insurance quotes because insurers look beyond the sticker price. In Canada, the CLEAR system uses industry claims experience to estimate how often a specific vehicle is involved in claims, how costly those claims are, and how likely the vehicle is to be stolen. A new model with a poorer loss record can therefore cost more to insure than the older car it replaces, even when both are driven by the same person.
This is why switching from an aging sedan to a newer crossover can produce a surprise. The crossover may have excellent safety equipment, but if its make, model, and model year generate more frequent or more expensive claims, the insurer can price that risk into the policy. The driver’s record has not changed; the vehicle’s insurance profile has. Checking model-specific loss experience before signing a purchase agreement can reveal this difference early.
Your Car Is Simply Worth More
A new vehicle usually puts more money at risk in a collision, theft, or total-loss claim. Canadian insurance guidance explicitly identifies vehicle value as one of the factors that can affect premiums. If an insurer may have to pay substantially more to repair or replace the new car, the physical-damage portion of the policy can become more expensive even when the owner has a spotless driving history.
Consider someone replacing a ten-year-old compact worth a modest amount with a brand-new SUV costing several times more. Liability risk may not change dramatically, but the insurer’s potential payout for the vehicle itself certainly can. A severe crash that would have written off the old car for a relatively small settlement could create a much larger loss on the new one. That difference helps explain why a quote can jump immediately after a vehicle swap, long before the owner has accumulated any driving history in the replacement car.
Minor Crashes Can Cost Much More to Repair
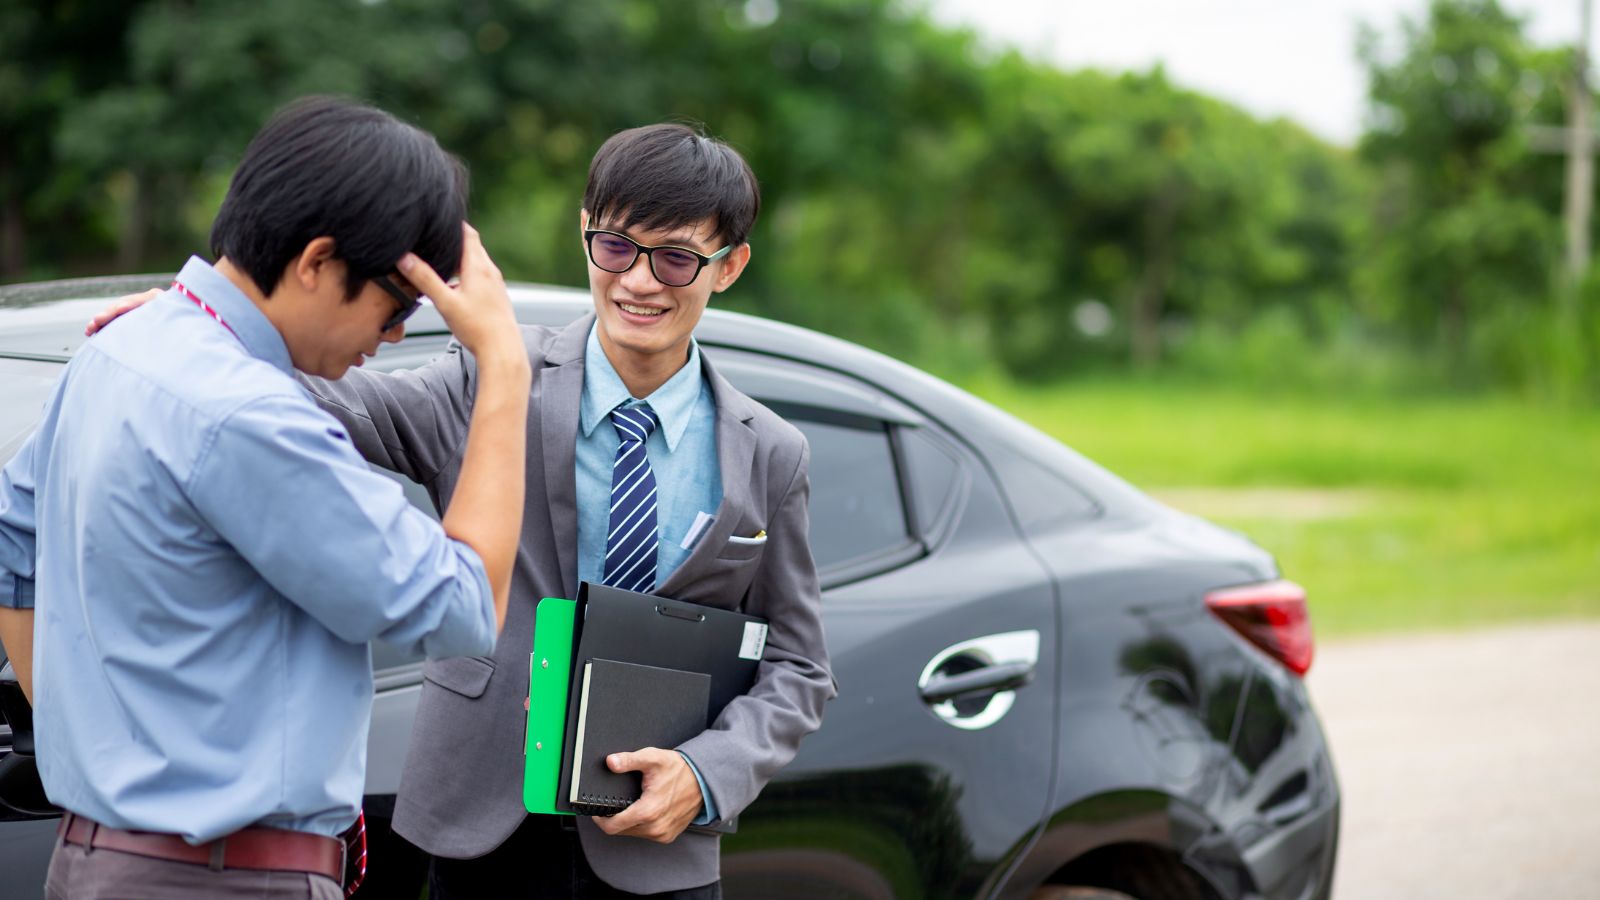
Modern vehicles pack cameras, sensors, electronics, specialized lighting, and complex body components into areas that used to be comparatively simple. Ontario’s insurance regulator has specifically linked newer vehicle technology, parts prices, and labour costs to rising physical-damage claim costs. A bumper scrape can now involve more than paint and plastic if radar units, parking sensors, wiring, or mounting brackets are damaged at the same time.
That repair reality matters to premiums because insurers price expected claim costs, not just the chance that a crash will happen. FSRA has reported that physical-damage costs per claim rose materially over a five-year period, with parts and labour among the pressures. For an owner moving from an older, mechanically simpler car into a technology-heavy replacement, the insurance increase may be reflecting the cost of restoring that vehicle properly after an accident. The car can be safer and still be more expensive to fix when something goes wrong.
ADAS Calibration Adds a New Layer of Cost
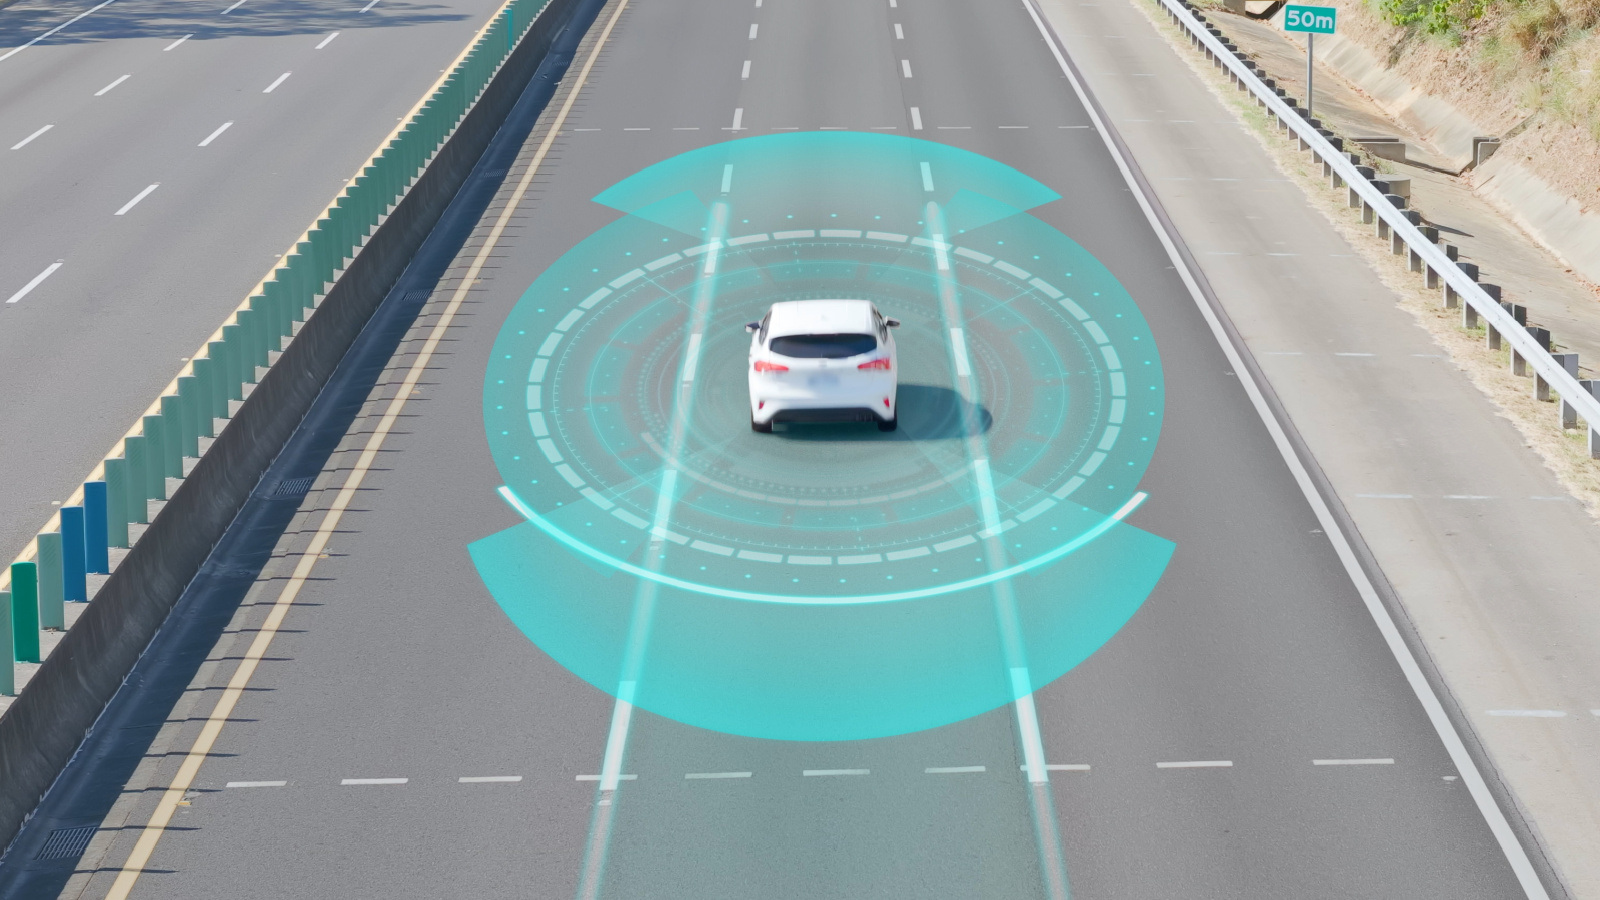
Advanced driver-assistance systems can reduce crashes, but they also change what happens after a repair. Cameras and radar used for features such as automatic emergency braking, lane keeping, and blind-spot monitoring may require scanning, aiming, or calibration after parts are removed, replaced, or even disturbed. Those procedures add labour, equipment, and documentation to repairs that once ended when the bodywork was finished.
Industry data shows how common this has become. CCC reported that calibrations appeared on more than one-third of repairable direct-repair appraisals in the third quarter of 2025, while scans appeared on nearly nine in ten. The Insurance Institute for Highway Safety has also noted that crash-avoidance technology can raise repair costs even while preventing many collisions. A new vehicle loaded with these systems may therefore present a different claims-cost profile than an older car without them, and insurers can account for that difference when setting premiums after repairs.
An EV Can Carry Higher Repair Severity
Buying an electric vehicle does not guarantee a higher insurance bill, but repair data shows why some EV owners receive larger quotes. Battery-electric vehicles combine high-voltage components, dense electronics, software-driven systems, and extensive diagnostic requirements. When those vehicles are damaged, repairers may need specialized training, safety procedures, scans, calibrations, and more original-equipment parts, all of which can influence claim severity.
Mitchell’s second-quarter 2026 Canadian data put average repairable claim severity for battery-electric vehicles at $6,645, compared with $5,411 for internal-combustion vehicles. The gap has been narrowing, so it would be misleading to treat every EV as expensive to insure. Model, location, driver, and coverage still matter. However, someone replacing a conventional gasoline car with an EV may be moving into a vehicle category whose repair economics are different enough to affect the quote, especially when the model itself also has expensive components or limited repair alternatives as well.
Your New Vehicle Is a Bigger Theft Target
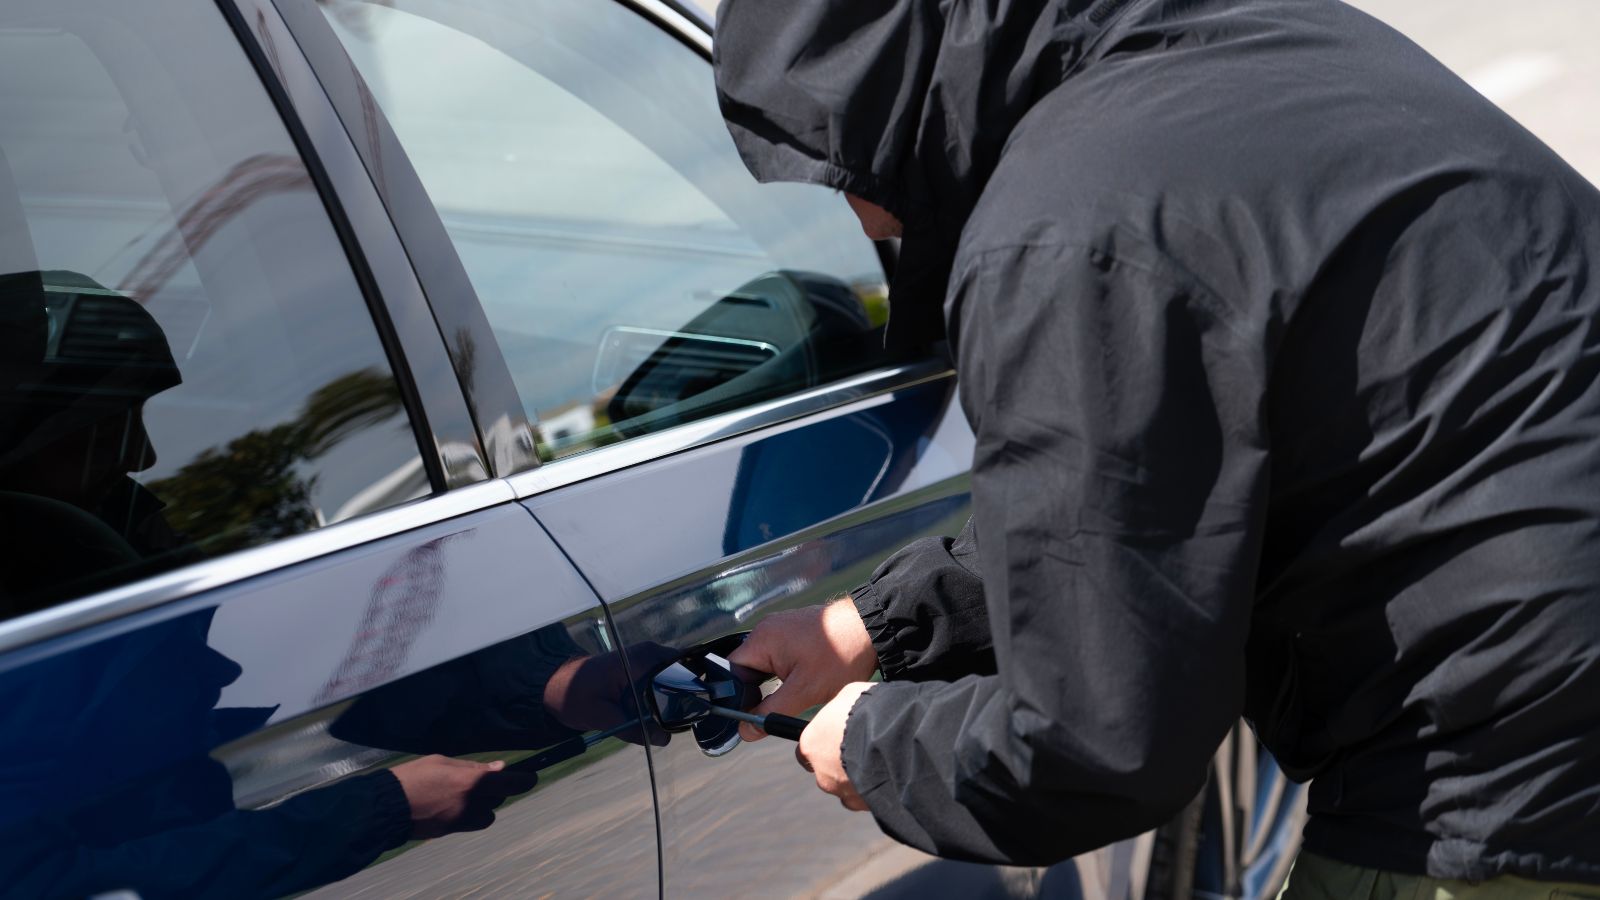
Theft risk can change dramatically from one vehicle to another, and insurers pay close attention to it. Canada’s CLEAR system includes theft likelihood in vehicle loss experience, while provincial regulators acknowledge that rising theft costs can feed into premiums. A model that is frequently targeted by organized theft rings may therefore produce a noticeably higher comprehensive premium than a less desirable or harder-to-steal vehicle.
The scale remains significant even after recent improvements. Équité Association reported that Canadian auto theft fell 18 percent in 2025 from the previous year, yet insurance claims still totalled an estimated $900 million. That means a buyer can choose a perfectly reliable, mainstream vehicle and still encounter an insurance shock because thieves want it. In some high-risk situations, insurers may also encourage additional anti-theft measures through discounts or risk-control programs. A quick insurance quote before purchase can reveal whether a popular new SUV or pickup carries a theft-related premium penalty in a particular region.
The Trim Level Changes the Insurance Math
Two versions of the same model can cost different amounts to insure. Insurers can consider the vehicle’s year, features, repair costs, and other characteristics, and ICBC specifically notes that trim options help determine premiums. A higher trim may bring larger wheels, expensive lighting, panoramic glass, extra cameras, premium body pieces, or other equipment that increases the cost of repairing or replacing damaged components.
This is easy to miss at the dealership because the monthly payment difference between trims can look manageable. Insurance pricing, however, sees the entire risk package. A luxury-oriented version of a compact SUV may share its engine and basic body shell with the entry model while carrying thousands of dollars in additional equipment. If a collision damages those parts, the insurer’s expected claim can be higher. Buyers comparing trims often focus on purchase price, fuel economy, and resale value, but an insurance quote for the exact trim can uncover another recurring cost before the contract is signed.
You Added Collision Coverage Again
Owners of older cars sometimes drop collision coverage because the vehicle’s value no longer justifies paying for protection against damage from an at-fault crash or impact with an object. Replacing that car with a new one often reverses the decision. Adding collision coverage back to the policy raises the amount of protection being purchased, so the premium can rise even if the insurer’s view of the driver has not changed at all.
Ontario’s regulator lists collision coverage among the optional protections that can increase premiums. The practical difference can be substantial: an owner may have carried only the minimum or near-minimum protection on a twelve-year-old car, then choose much broader coverage on a new $45,000 replacement. The resulting bill can feel like a penalty for buying new, but part of the increase is simply the cost of insuring the vehicle itself against crash damage. Comparing the old and new declarations pages can show how much coverage changed alongside the vehicle.
You Added Comprehensive Coverage
Comprehensive coverage protects against risks that are not ordinary collision losses, including theft, vandalism, and certain weather or glass losses, depending on the policy and province. It is commonly retained on newer vehicles because the owner has far more money tied up in the car. If the previous vehicle carried no comprehensive coverage, adding it to the replacement can make the new premium look sharply higher.
The reason is straightforward: the insurer has taken on more types of potential claims. Canada’s Financial Consumer Agency describes comprehensive insurance as protection that can include theft, vandalism, and windshield damage, while FSRA notes that buying additional protection generally increases premiums. This can be especially noticeable for a new vehicle parked outdoors in a theft-prone urban area or exposed to hail. The comparison that matters is not just old car versus new car; it is old coverage versus new coverage. A cheaper policy may simply have been covering much less.
You Chose a Lower Deductible
New-car owners often become less comfortable with large out-of-pocket repair bills. That can lead them to lower the deductible on collision or comprehensive coverage when the new vehicle is added. The trade-off is simple: a smaller deductible means the insurer pays more of an eligible loss, so the customer generally pays a higher premium in exchange for that protection.
Canadian regulators make this relationship clear. FSRA states that, as a general rule, lower deductibles mean higher premiums, while ICBC explains the reverse: higher deductibles reduce premium costs. Imagine moving from a $1,000 collision deductible on an older car to $500 on a new one. The owner has reduced the amount personally absorbed after a covered claim, which shifts more potential cost to the insurer. The premium increase may therefore reflect a deliberate coverage choice rather than the vehicle alone. Reviewing deductible changes can explain part of an unexpectedly large quote.
You Added New-Vehicle Replacement Protection
A brand-new vehicle creates a problem that an older car does not: depreciation can begin almost immediately, while the owner may still owe or have paid close to the original purchase price. Many drivers respond by buying a limited waiver of depreciation or similar new-vehicle replacement protection. This endorsement can improve a total-loss settlement, but additional protection is not free and can increase the premium.
Insurance Bureau of Canada describes limited waiver of depreciation as coverage available when buying, leasing, or financing a new vehicle that can preserve replacement value for a specified period. Ontario’s OPCF 43 serves a similar purpose by removing the insurer’s right to deduct depreciation in qualifying total-loss situations. For a buyer comparing the new bill with an old policy, this endorsement can be an overlooked difference. The higher premium may partly be paying for a better claim settlement if the new car is stolen or written off soon after purchase.
Your Lease or Loan Requires Broader Protection
Financing or leasing can change the minimum coverage a driver is willing—or contractually allowed—to carry. Lenders and leasing companies have a financial interest in the vehicle and may require collision, comprehensive, specified deductibles, or minimum liability limits. That means someone moving from an owned older car with lean coverage to a leased new vehicle may have little choice but to buy a broader policy.
Ford Credit provides a clear Canadian example: its leased vehicles require at least $1 million in third-party liability plus collision or all-perils and comprehensive coverage, with deductibles subject to limits. Requirements vary by lender and contract, so this is not a universal rule. Still, the mechanism is common. The insurance increase may appear immediately after the new-car purchase because the financing agreement changed the coverage floor. Before comparing premiums, buyers should compare what each policy actually includes and check the lease or loan documents for insurance conditions.
You Raised Liability or Accident-Benefit Limits
A vehicle purchase is often when people review the entire policy, not just the car being insured. A broker may discuss higher third-party liability limits, expanded accident benefits, rental-car protection, loss-of-use coverage, or other endorsements. Those additions can be sensible, but they also mean the policy is covering more risk, so the final premium may be higher than the old policy even if the new vehicle itself is not unusually expensive to insure.
Ontario provides a useful example. FSRA says consumers can buy higher liability limits and optional accident-benefit coverages, and that there is a cost to increasing protection. Since July 2026, Ontario’s accident-benefit structure also allows several choices beyond mandatory medical, rehabilitation, and attendant-care benefits. A driver replacing an older car might use the transaction as a prompt to strengthen coverage from $1 million to $2 million in liability or add optional benefits. The resulting increase belongs partly to the coverage upgrade, not just the vehicle switch.
You Expect to Drive More Kilometres
A new vehicle often becomes the household workhorse. The old car may have been used mostly for errands, while the new one starts handling commuting, weekend trips, school runs, and long-distance travel. Insurers care about that change because more kilometres generally mean more time exposed to traffic, weather, and collision risk. FSRA explicitly lists annual distance driven as a factor in calculating premiums.
The effect is visible in provincial programs as well. ICBC offers distance-based discounts to eligible drivers who stay below specified annual kilometre thresholds, illustrating how mileage can materially affect pricing. Someone who previously drove 6,000 kilometres a year but expects to put 20,000 on the new vehicle may lose low-mileage savings or enter a different risk category. The car did not suddenly make the driver riskier; the planned usage changed. When obtaining a quote, an accurate annual-kilometre estimate is important because a new vehicle often changes driving habits more than buyers expect.
The Car Is Now Used for Commuting or Business
How a vehicle is used can matter as much as what it is. A replacement car that becomes the daily commuter, a salesperson’s road vehicle, or a delivery vehicle may be assigned a different use classification from an old car that was insured mainly for pleasure. More structured or commercial use can change exposure, mileage, driving times, and the environments in which the vehicle operates.
ICBC, for example, uses different rate classes for pleasure, commuting, business, and delivery use. FSRA likewise notes that whether a vehicle is driven to work or school affects premiums. The practical trap is assuming that transferring the old policy automatically preserves the old price. If the new purchase also marks a lifestyle change—returning to the office, taking a job with regular client visits, or beginning app-based delivery work—the insurer may re-rate the policy accordingly. Accurate disclosure matters because the wrong use classification can also create coverage problems after a claim.
Another Driver Is Now Listed on the Vehicle
A new family vehicle often changes who drives what. A teenager may become an occasional driver, a spouse may use the new SUV more frequently, or a household member with less experience may be added to the policy. Depending on the province and insurer, the experience and claims history of listed drivers can influence the premium, so the vehicle purchase can trigger a price increase that is really about the people behind the wheel.
ICBC illustrates this clearly: its pricing model considers listed drivers, driving experience, and crash history, and in many cases the policy’s combined driver factor reflects more than just the principal driver. It also applies an additional premium for learner drivers. Other provinces use different systems, but the broader lesson is similar—driver information matters. Before blaming the new car for a higher quote, compare the driver list on the old and new policies. A newly added or newly reclassified household driver may explain part of the difference.
An Insurer-Wide Rate Change Hit at the Same Time
Sometimes the timing is misleading. A driver buys a new car, receives a higher insurance bill, and reasonably assumes the vehicle caused the entire increase. But insurers also adjust rates in response to changing claims costs, theft, repair inflation, driving patterns, and other market conditions. A vehicle change made near renewal can therefore coincide with a broader rate increase that would have affected the policy anyway.
Ontario offers a concrete example of why this matters. FSRA says insurers require approval for rate changes and notes that inflation, increased driving, theft, parts prices, and labour costs can put upward pressure on premiums. Its published Ontario average rose from $2,006 in October 2024 to $2,164 in October 2025. That does not mean every driver saw the same change, and provincial systems differ. It does show why the cleanest comparison is an insurer quote for the old and new vehicles using identical drivers, coverage, deductibles, usage, and effective date.
19 Used Cars Canadians Should Avoid in 2026 (Based on Owner Complaints)
Buying a used car in Canada can feel safe until repair bills start stacking up. Owner complaints tell a different story than glossy listings. Transmission failures, electrical problems, and weak winter reliability show up again and again in consumer reports. Many of these issues appear after warranties expire, when owners least expect them. Some vehicles look affordable upfront, but become expensive to keep on the road. Others struggle in cold weather, urban driving, or long highway commutes. Here are 19 used cars Canadians should avoid in 2026 (based on owner complaints).
19 Used Cars Canadians Should Avoid in 2026 (Based on Owner Complaints)